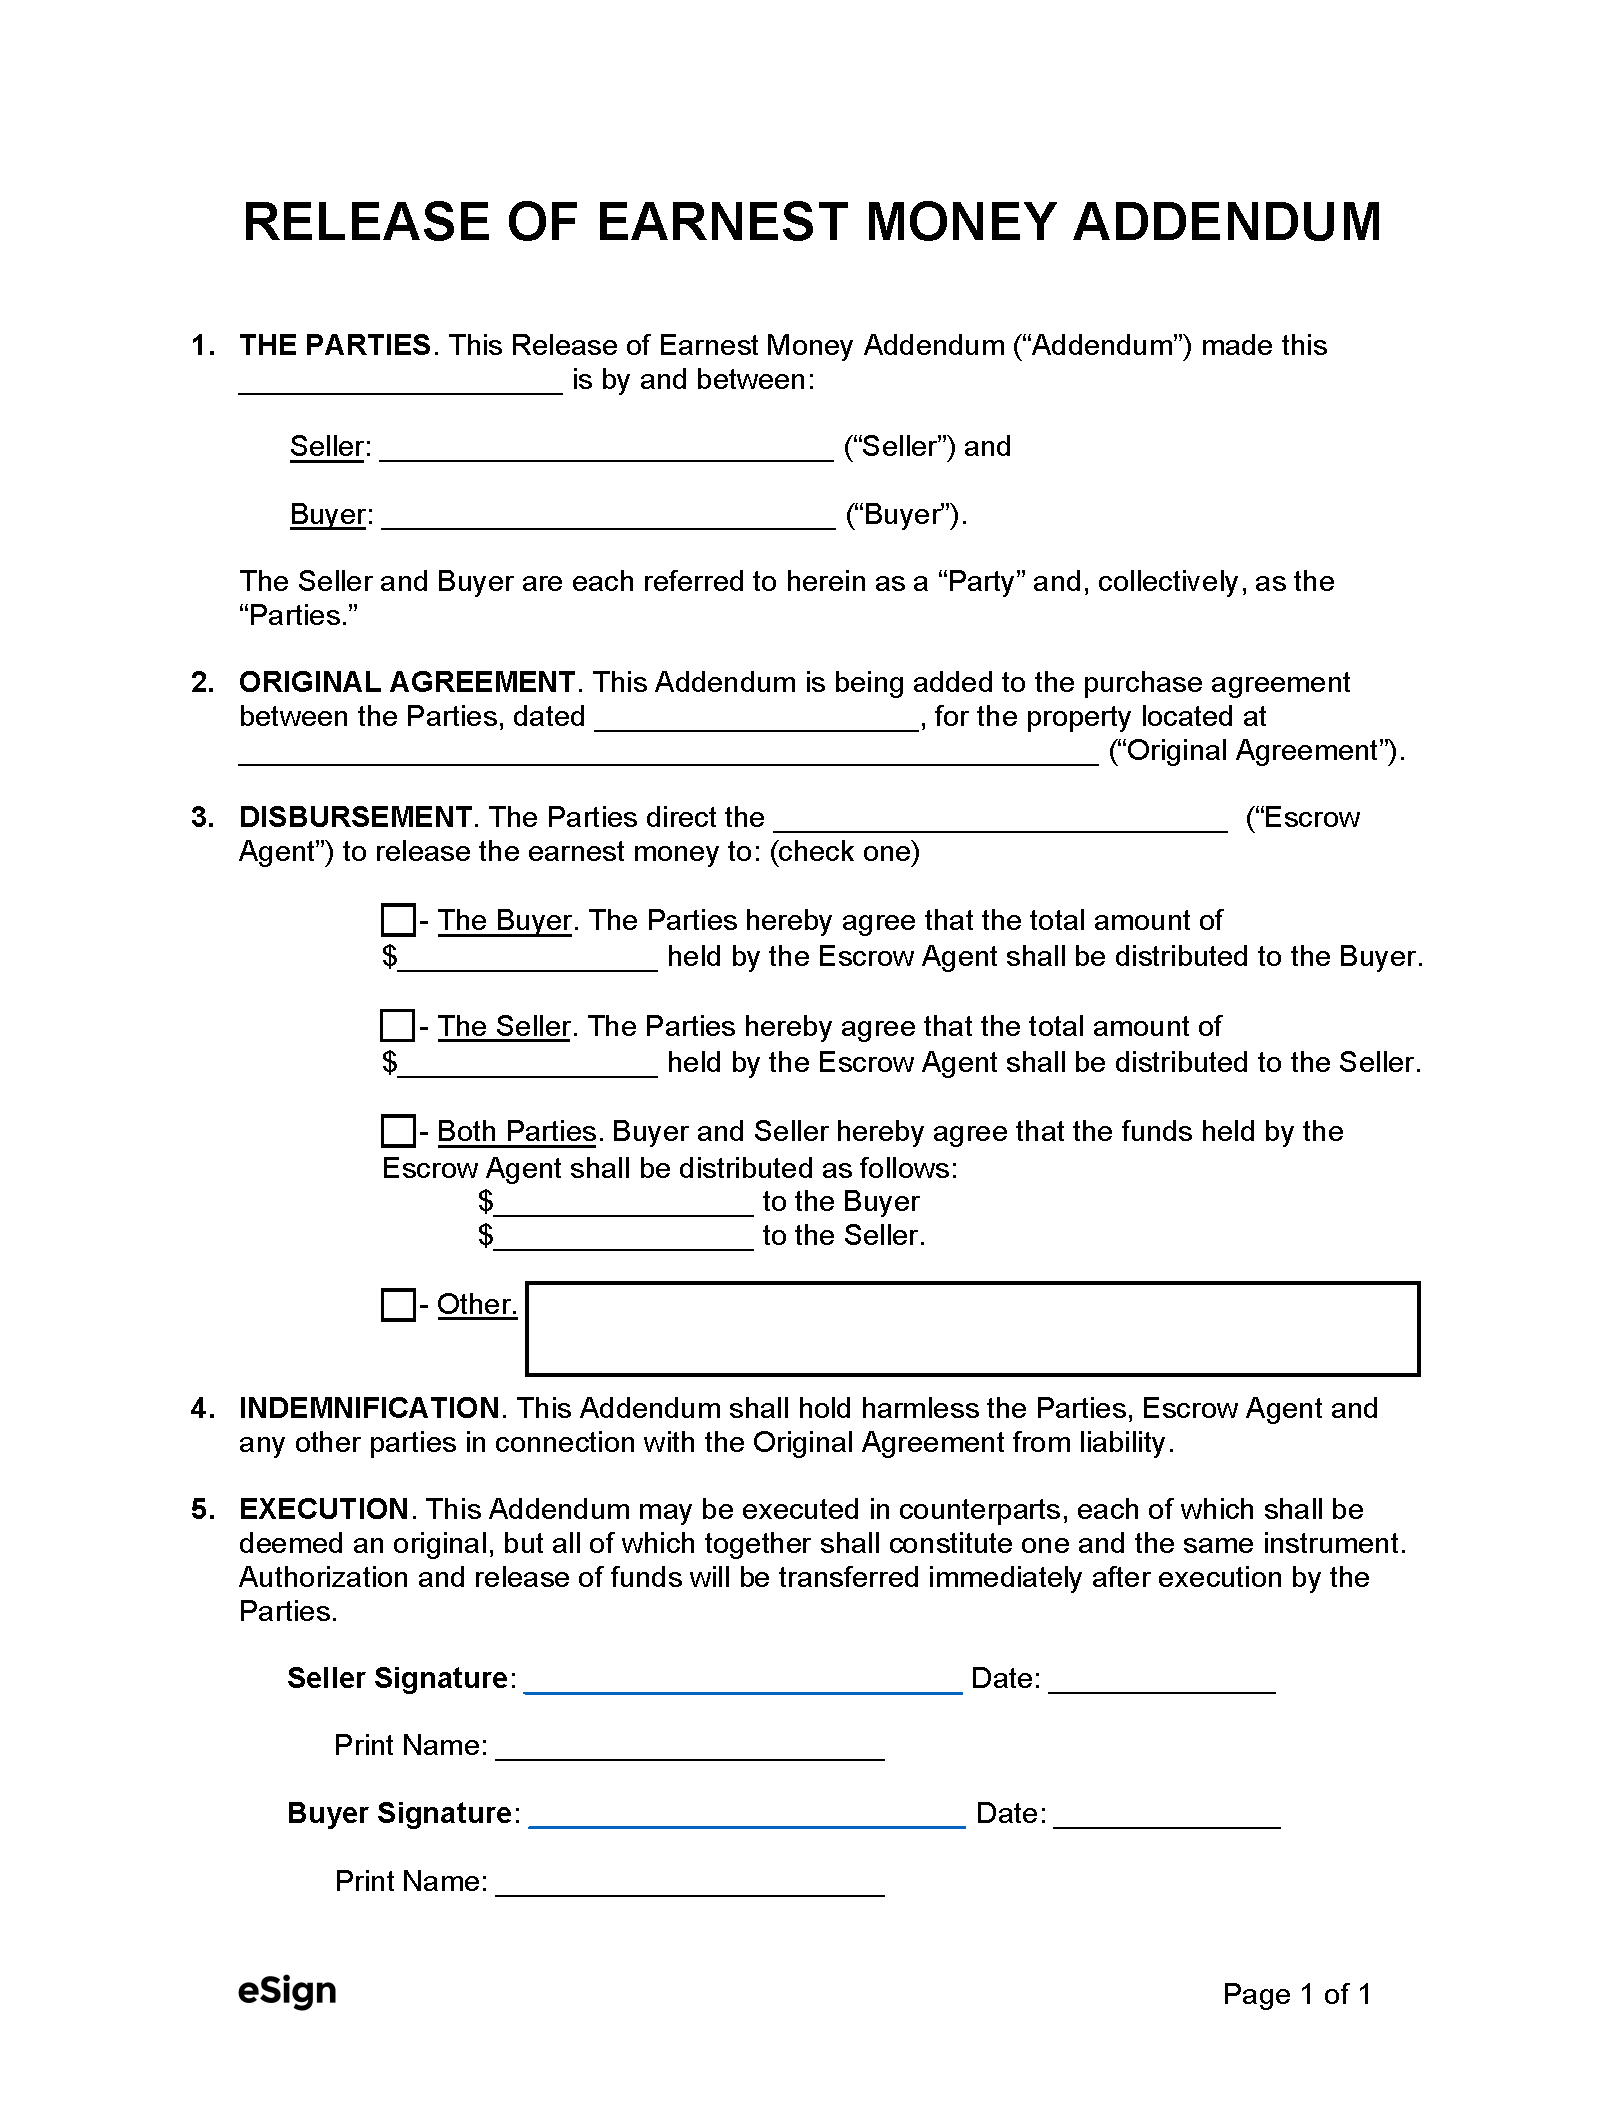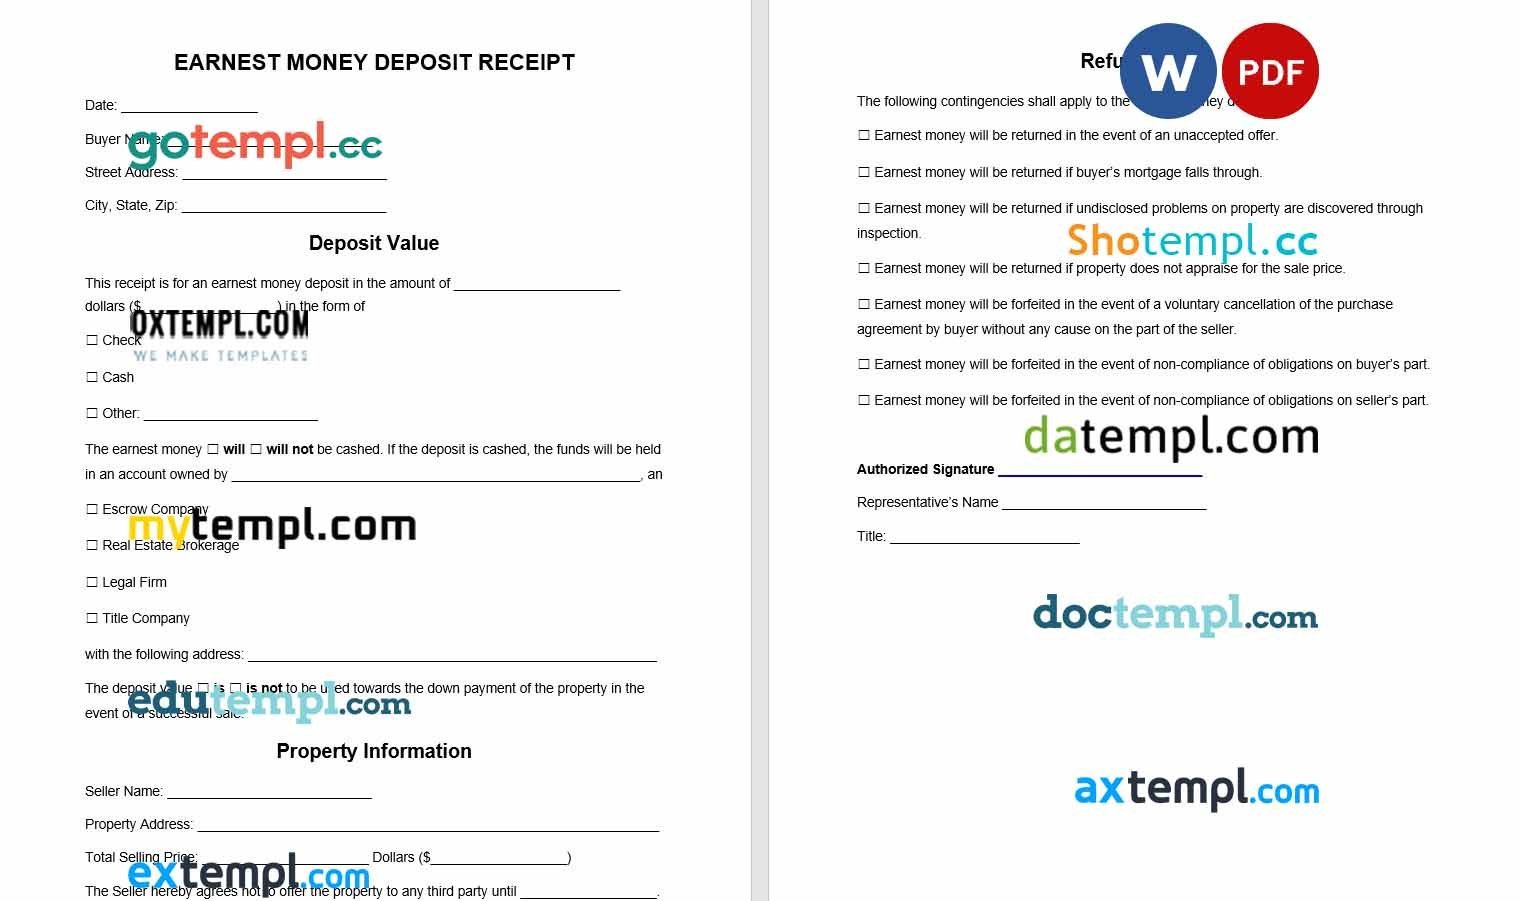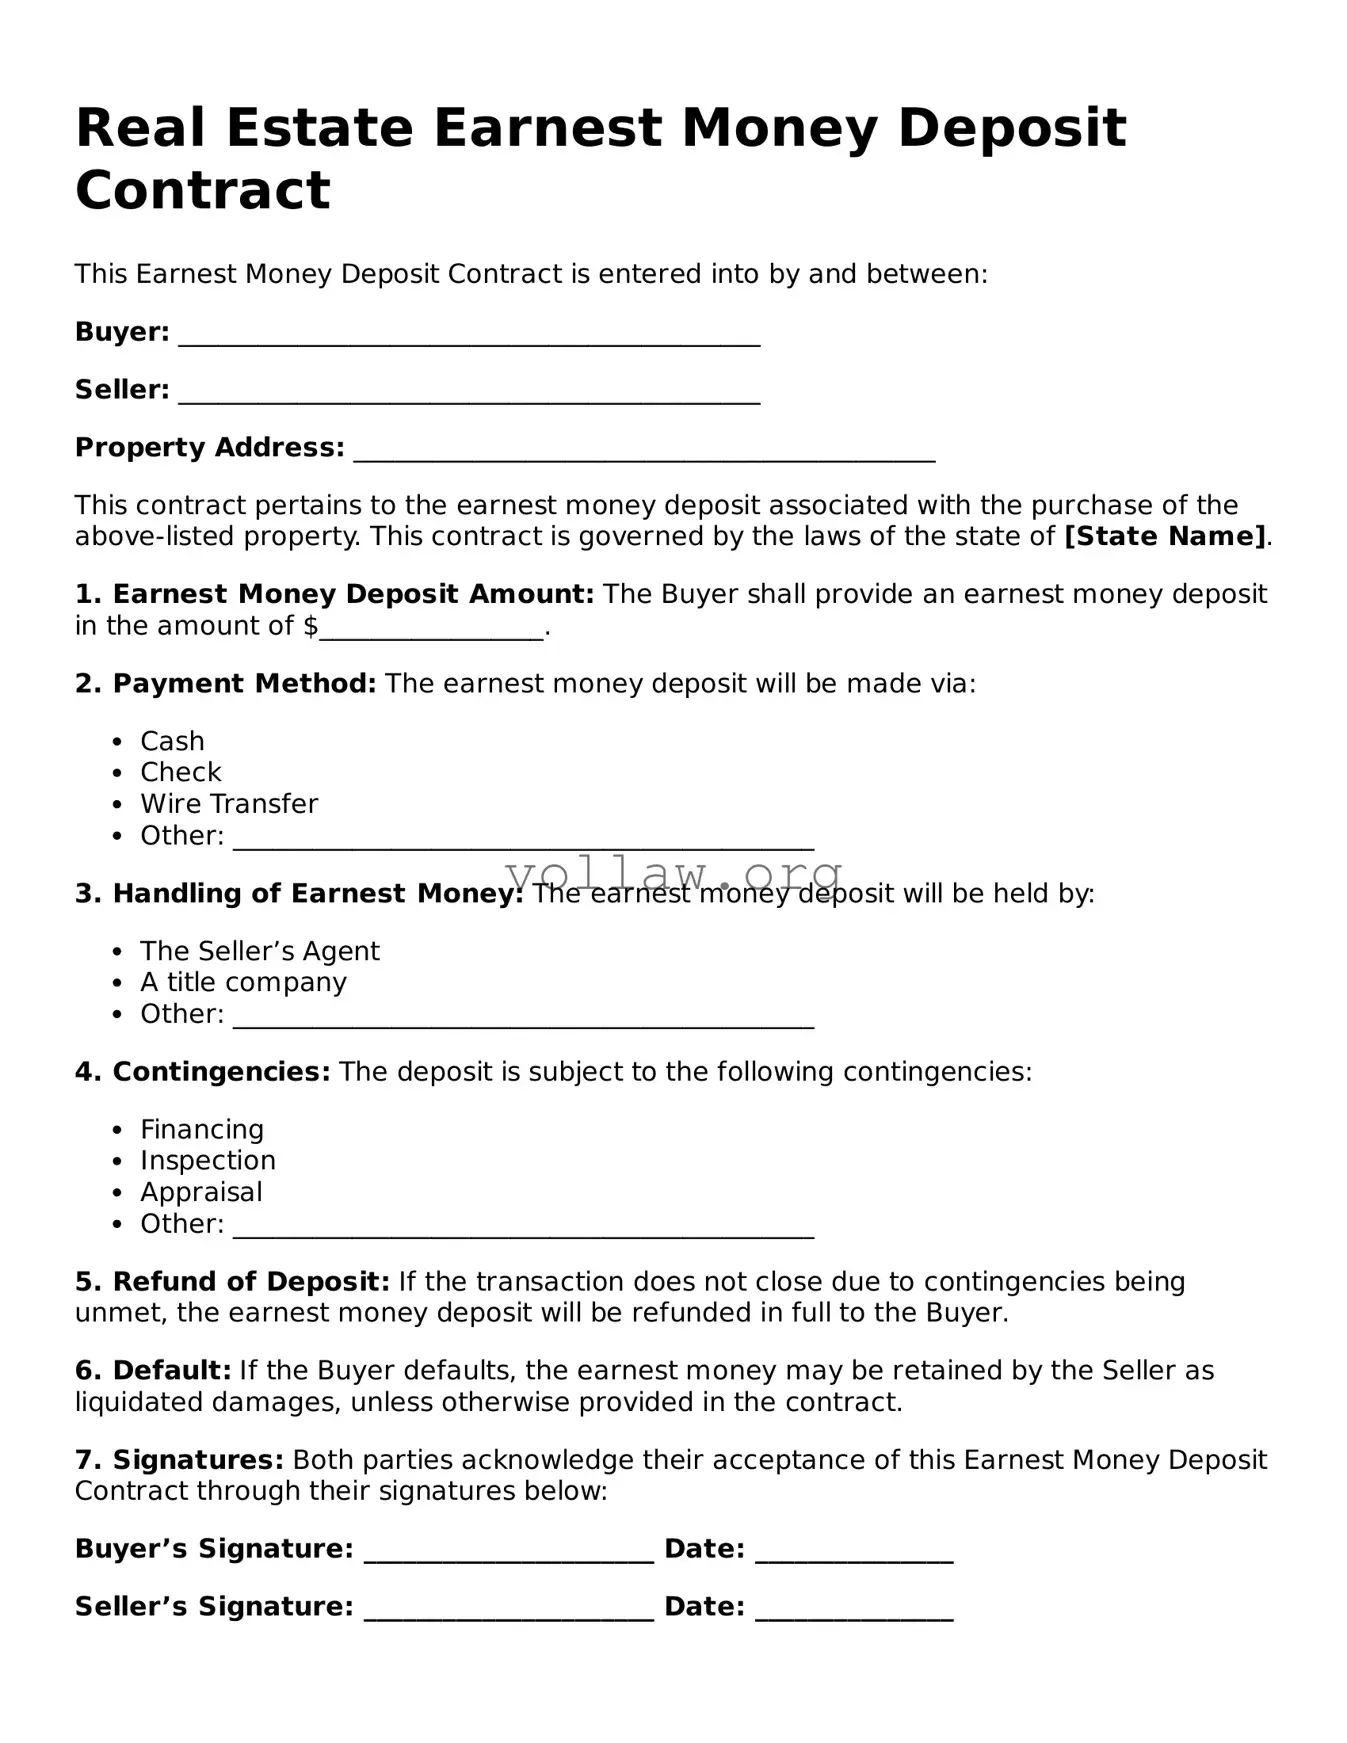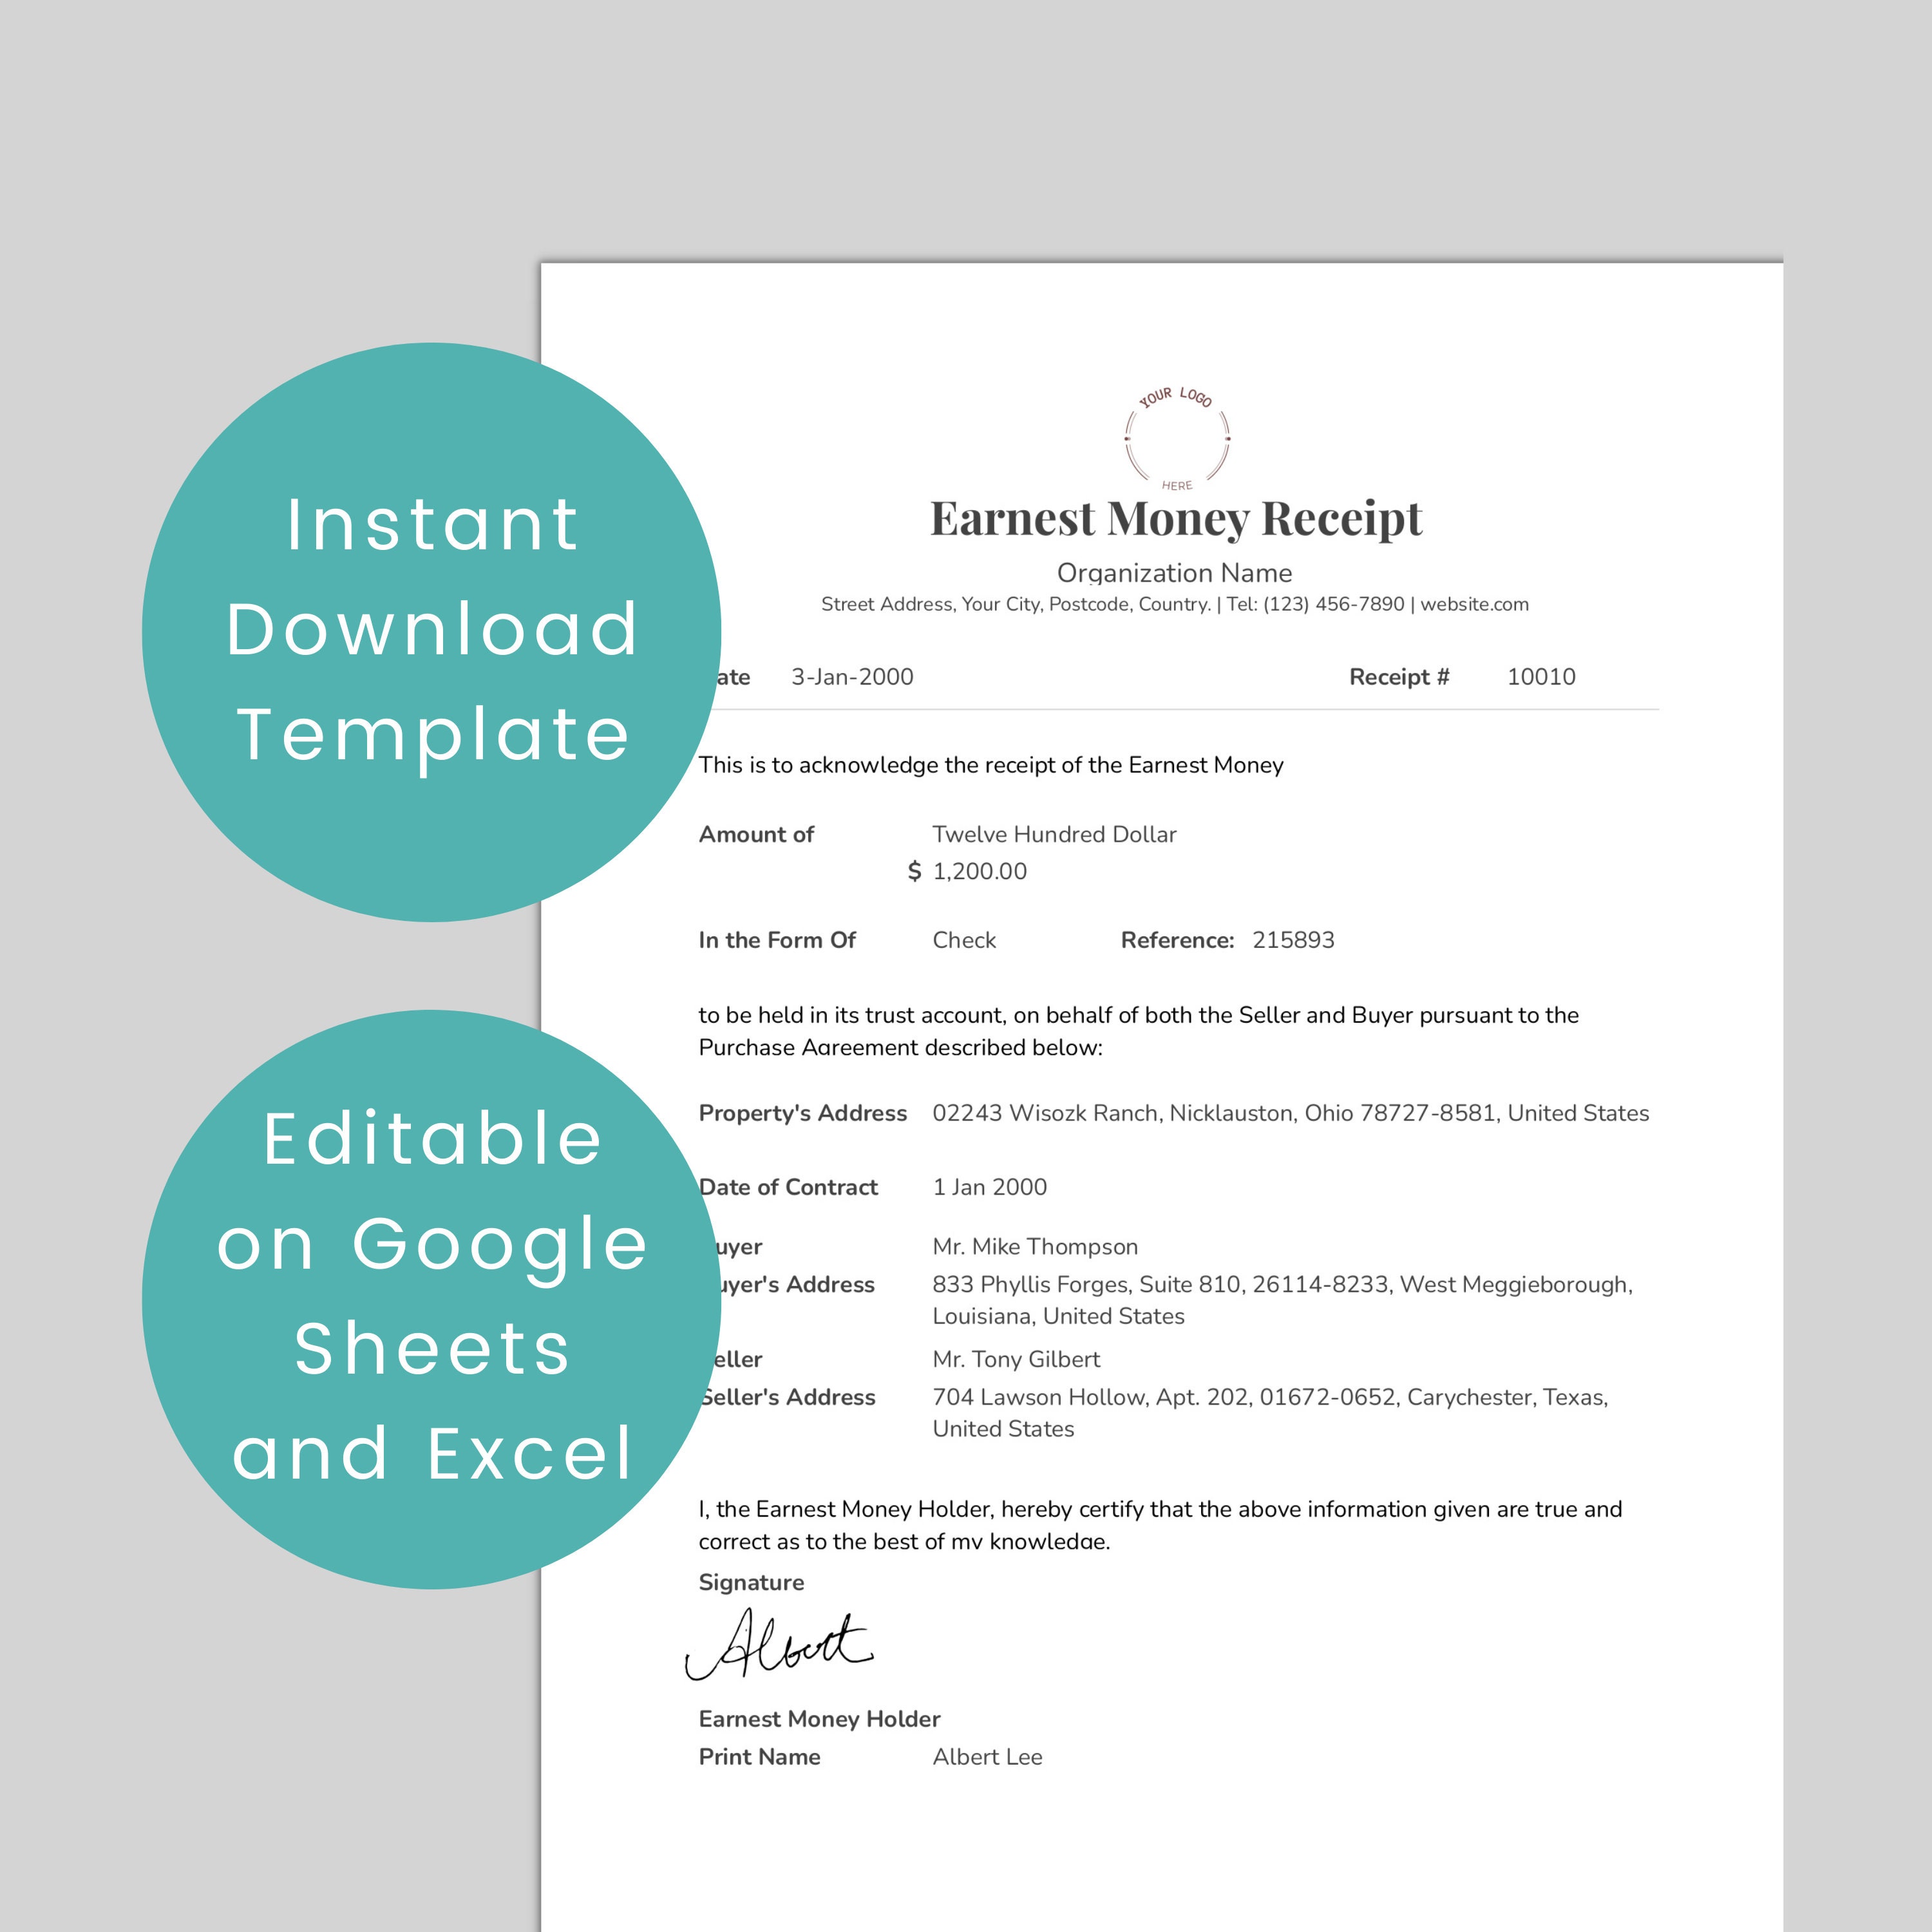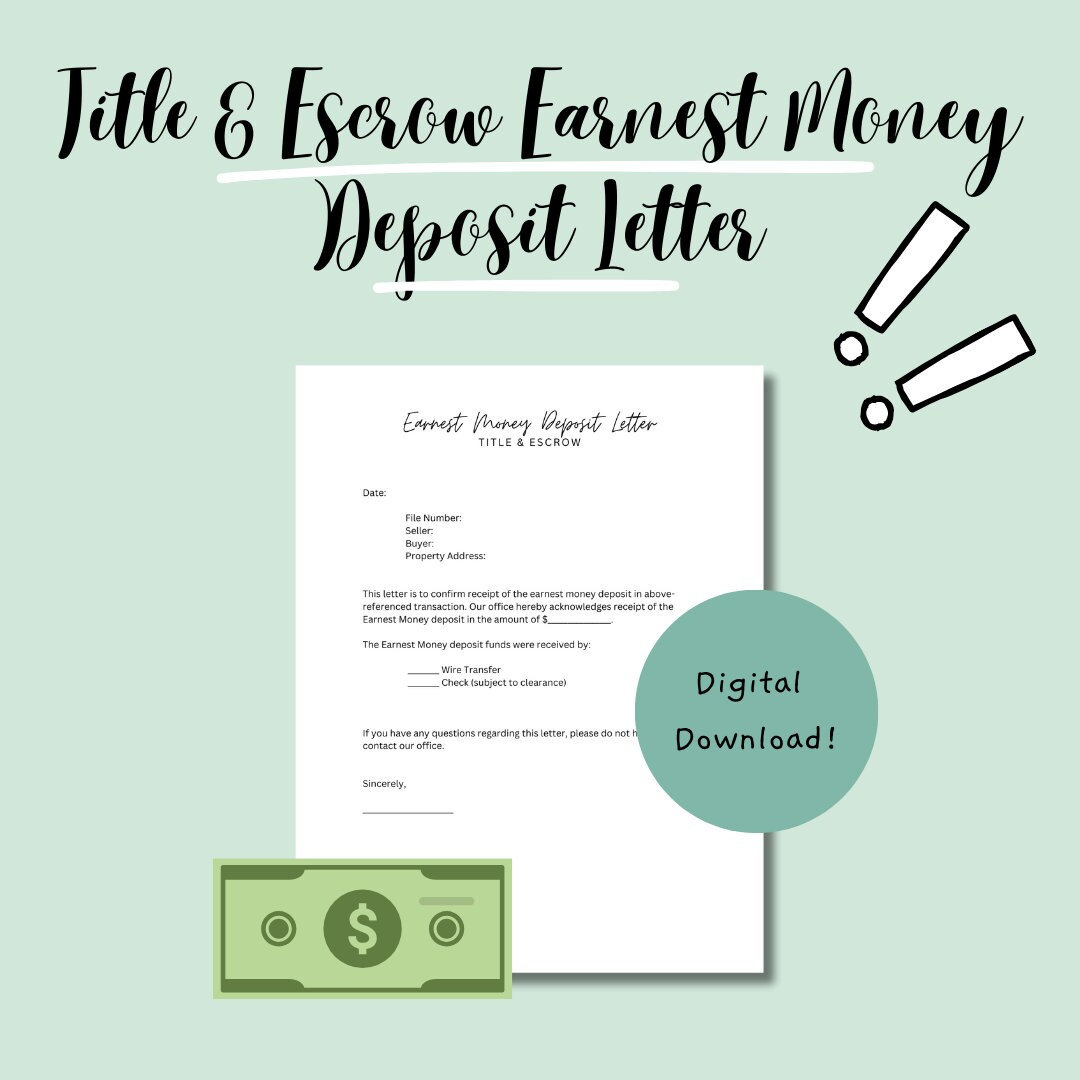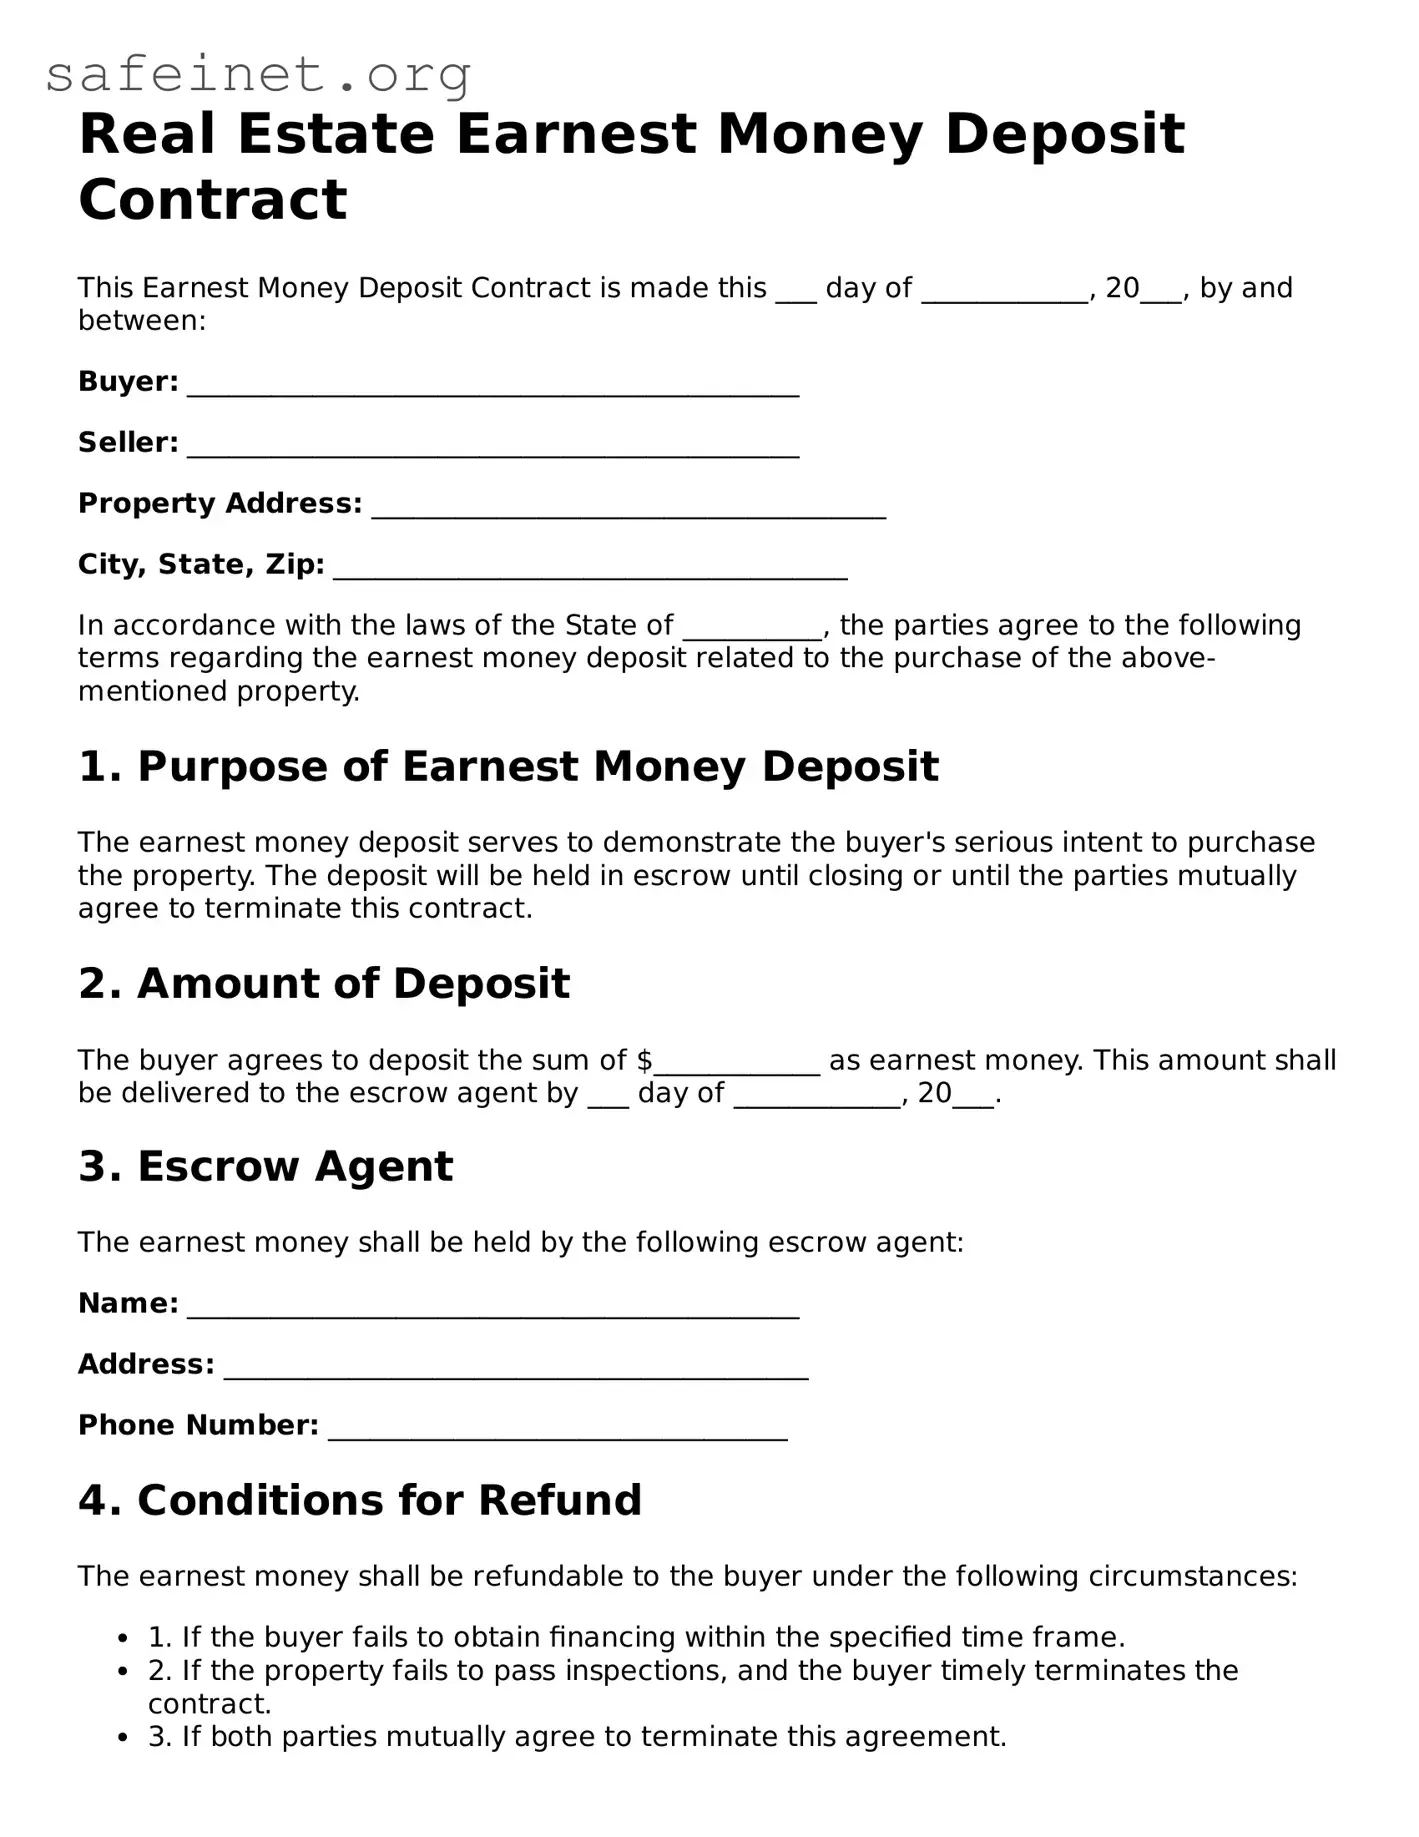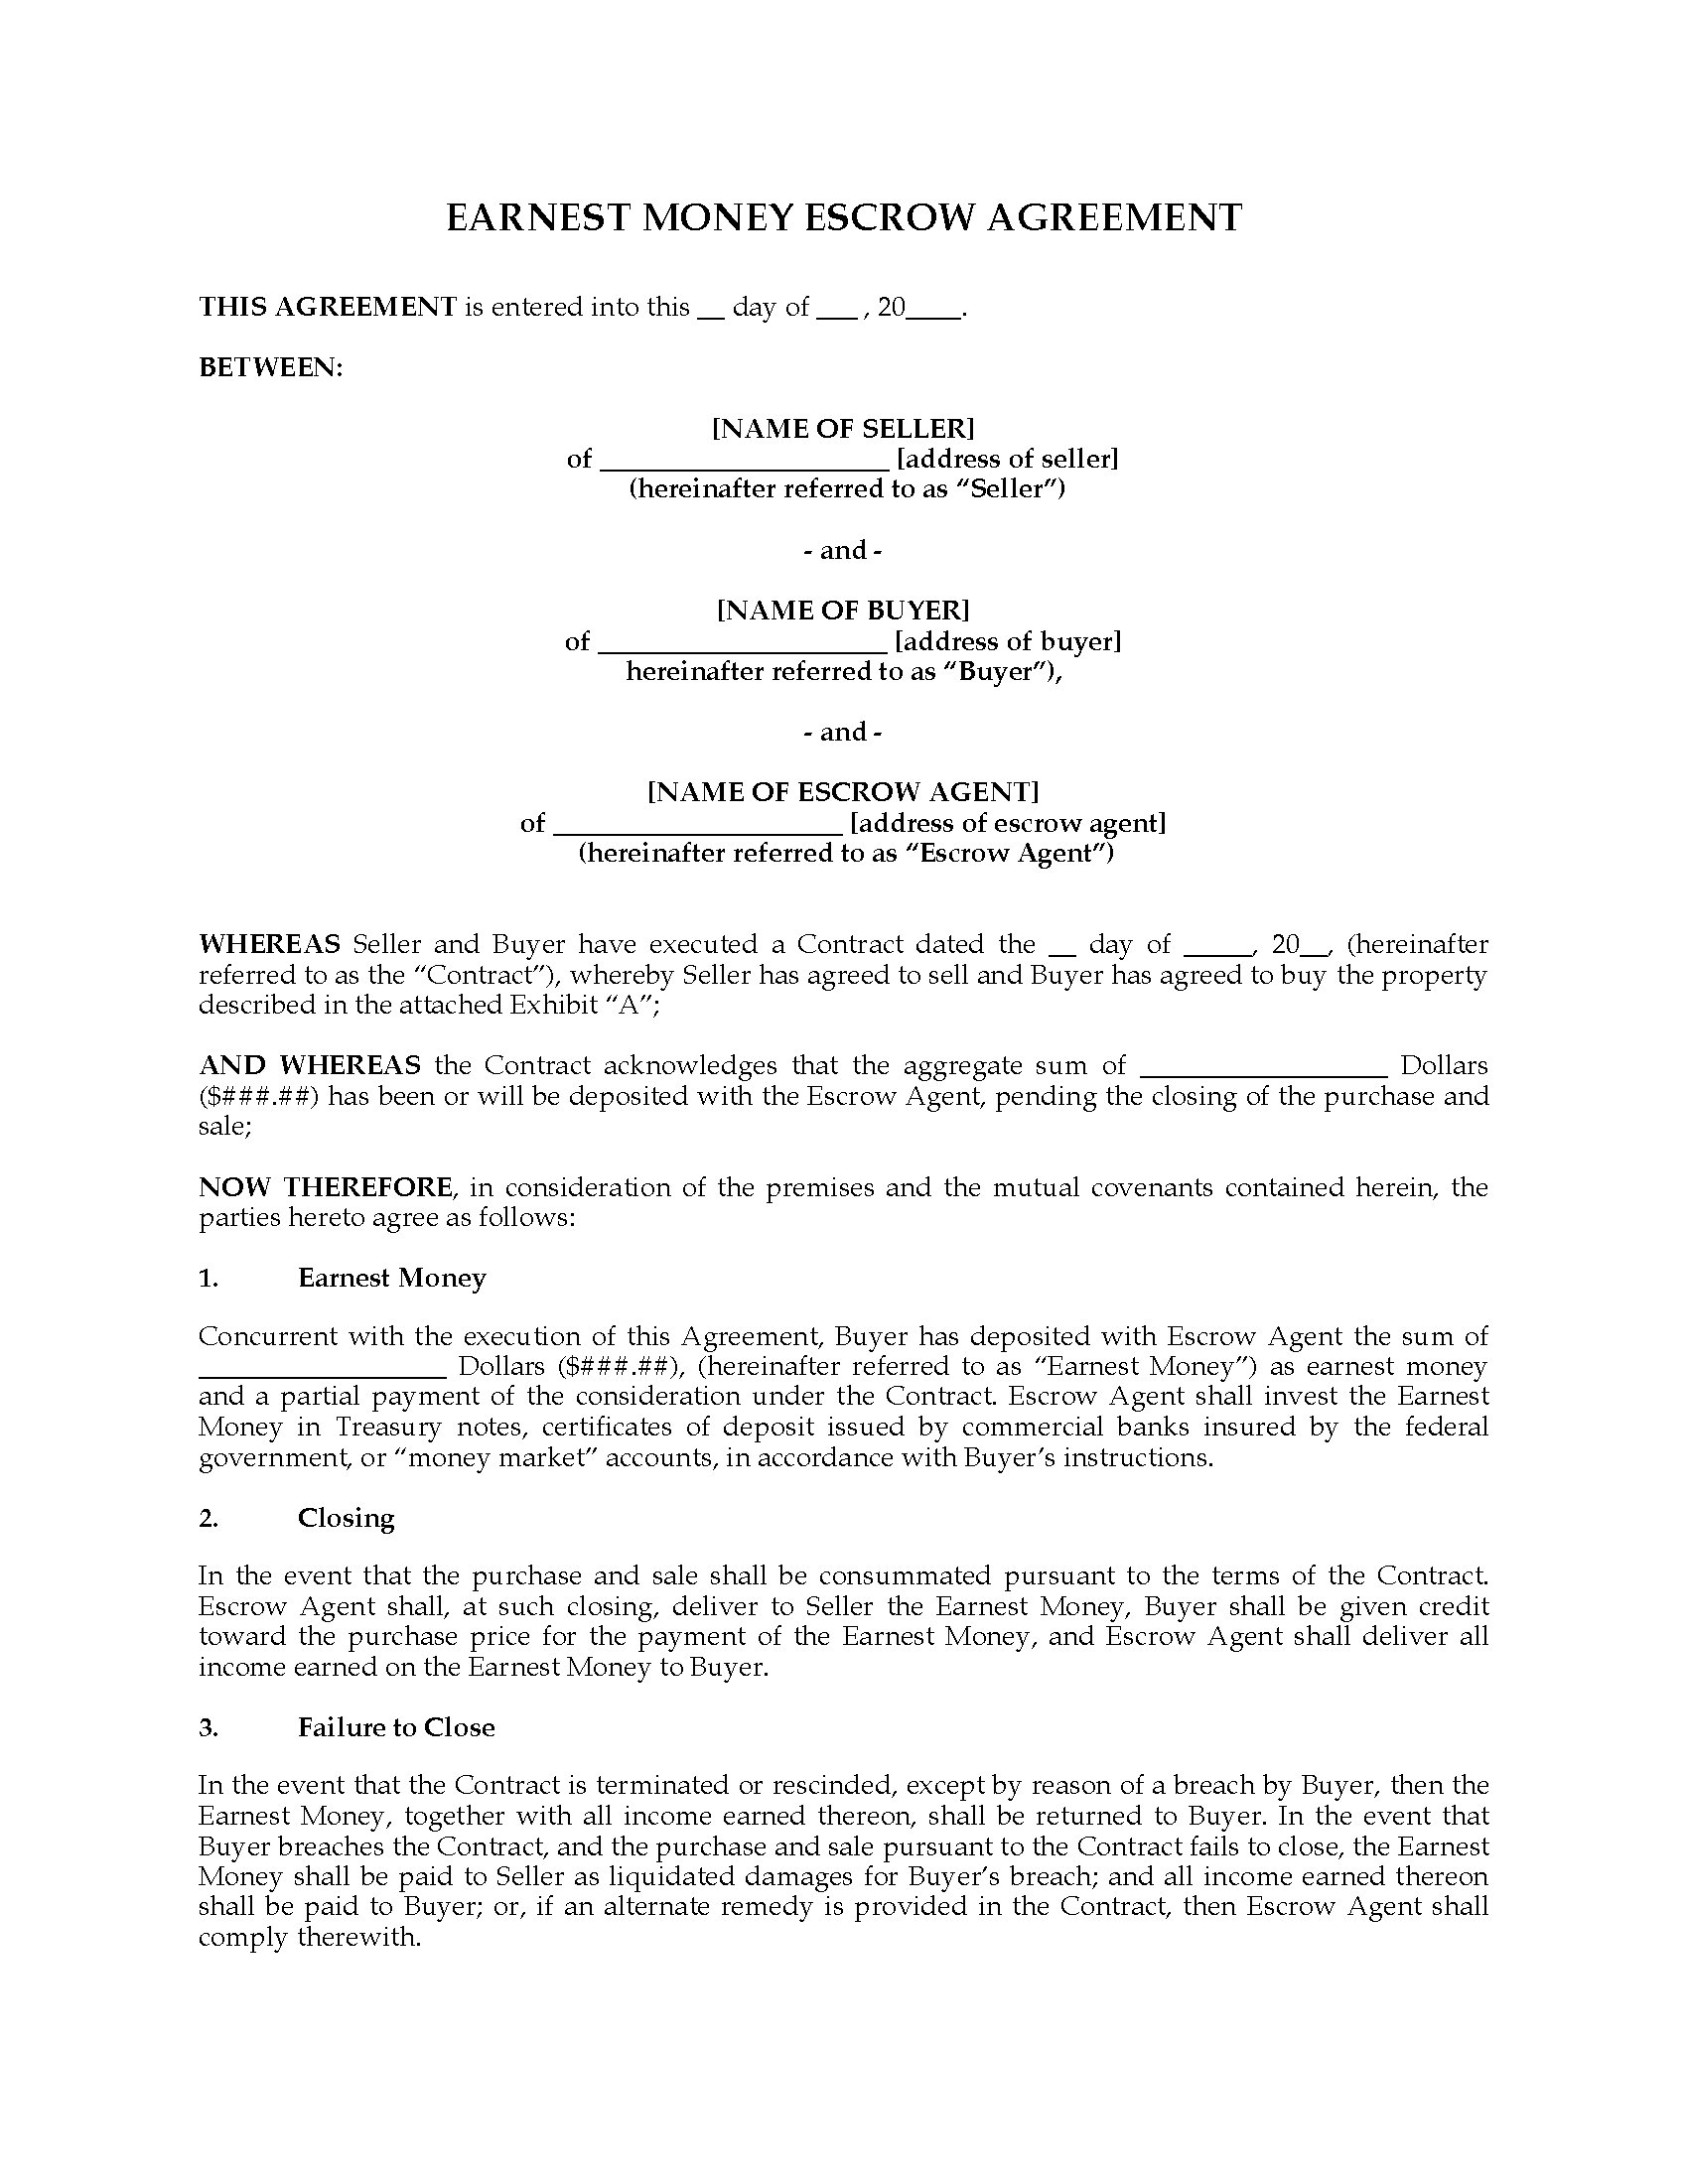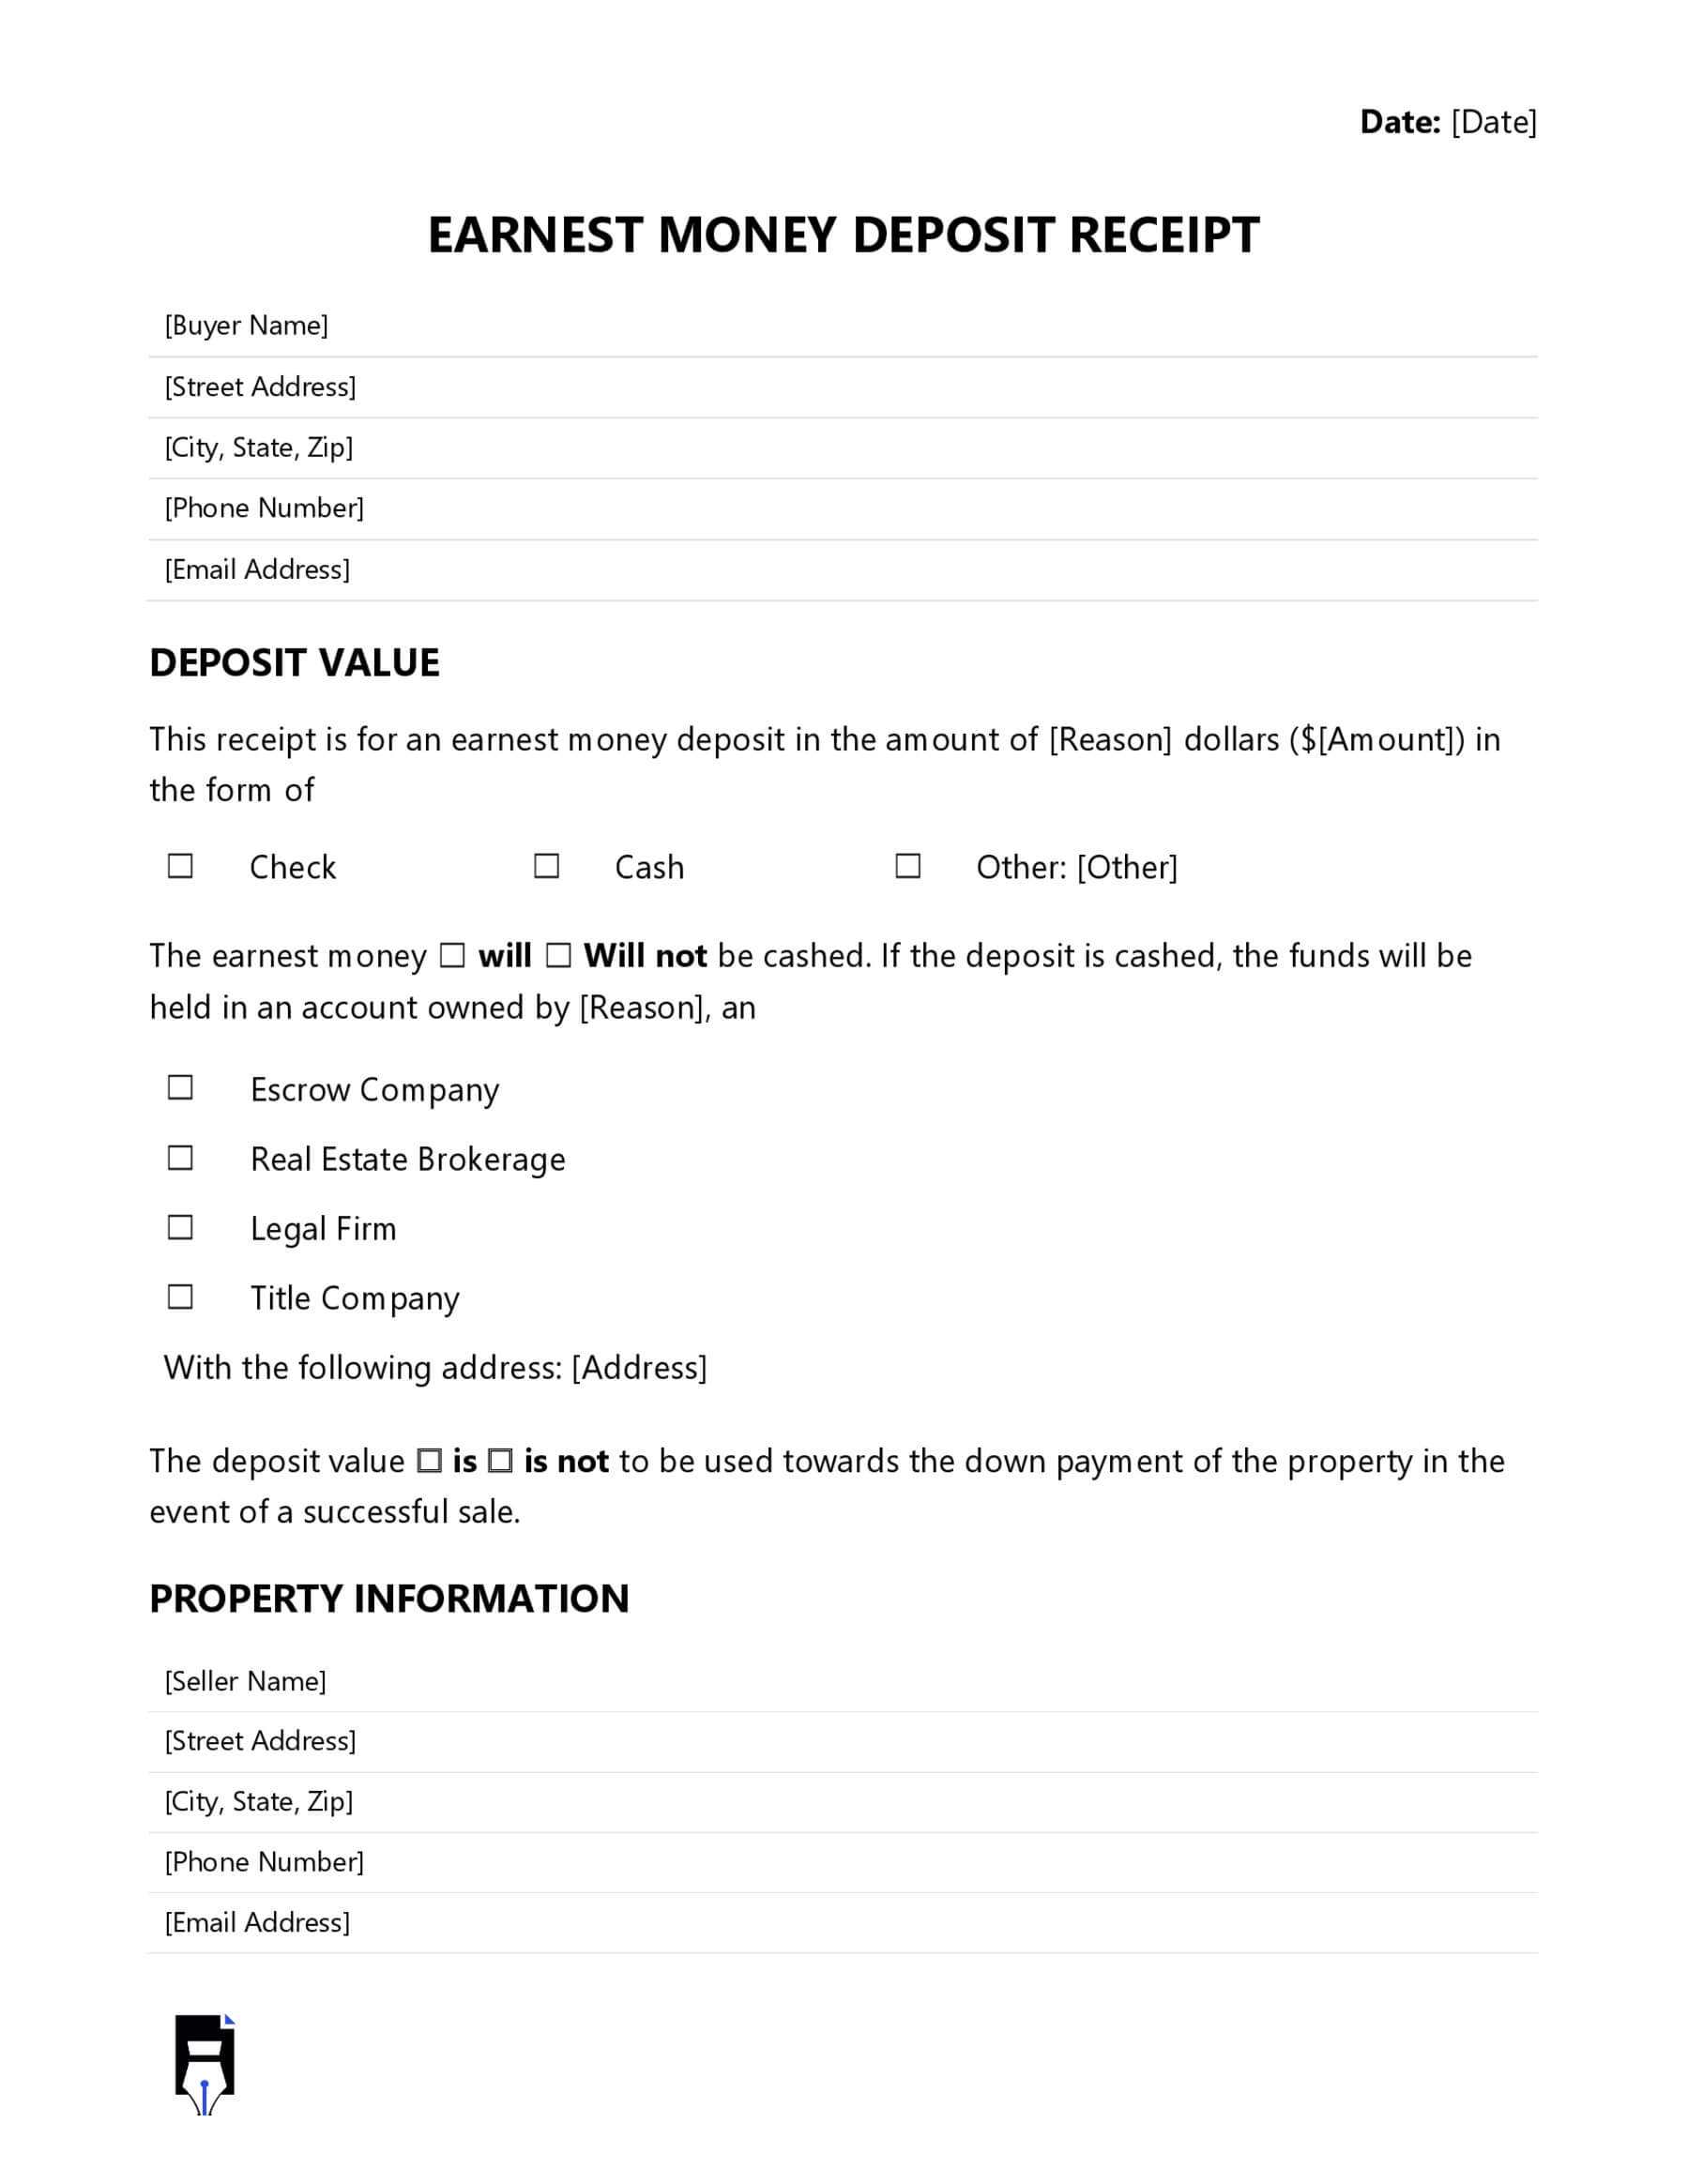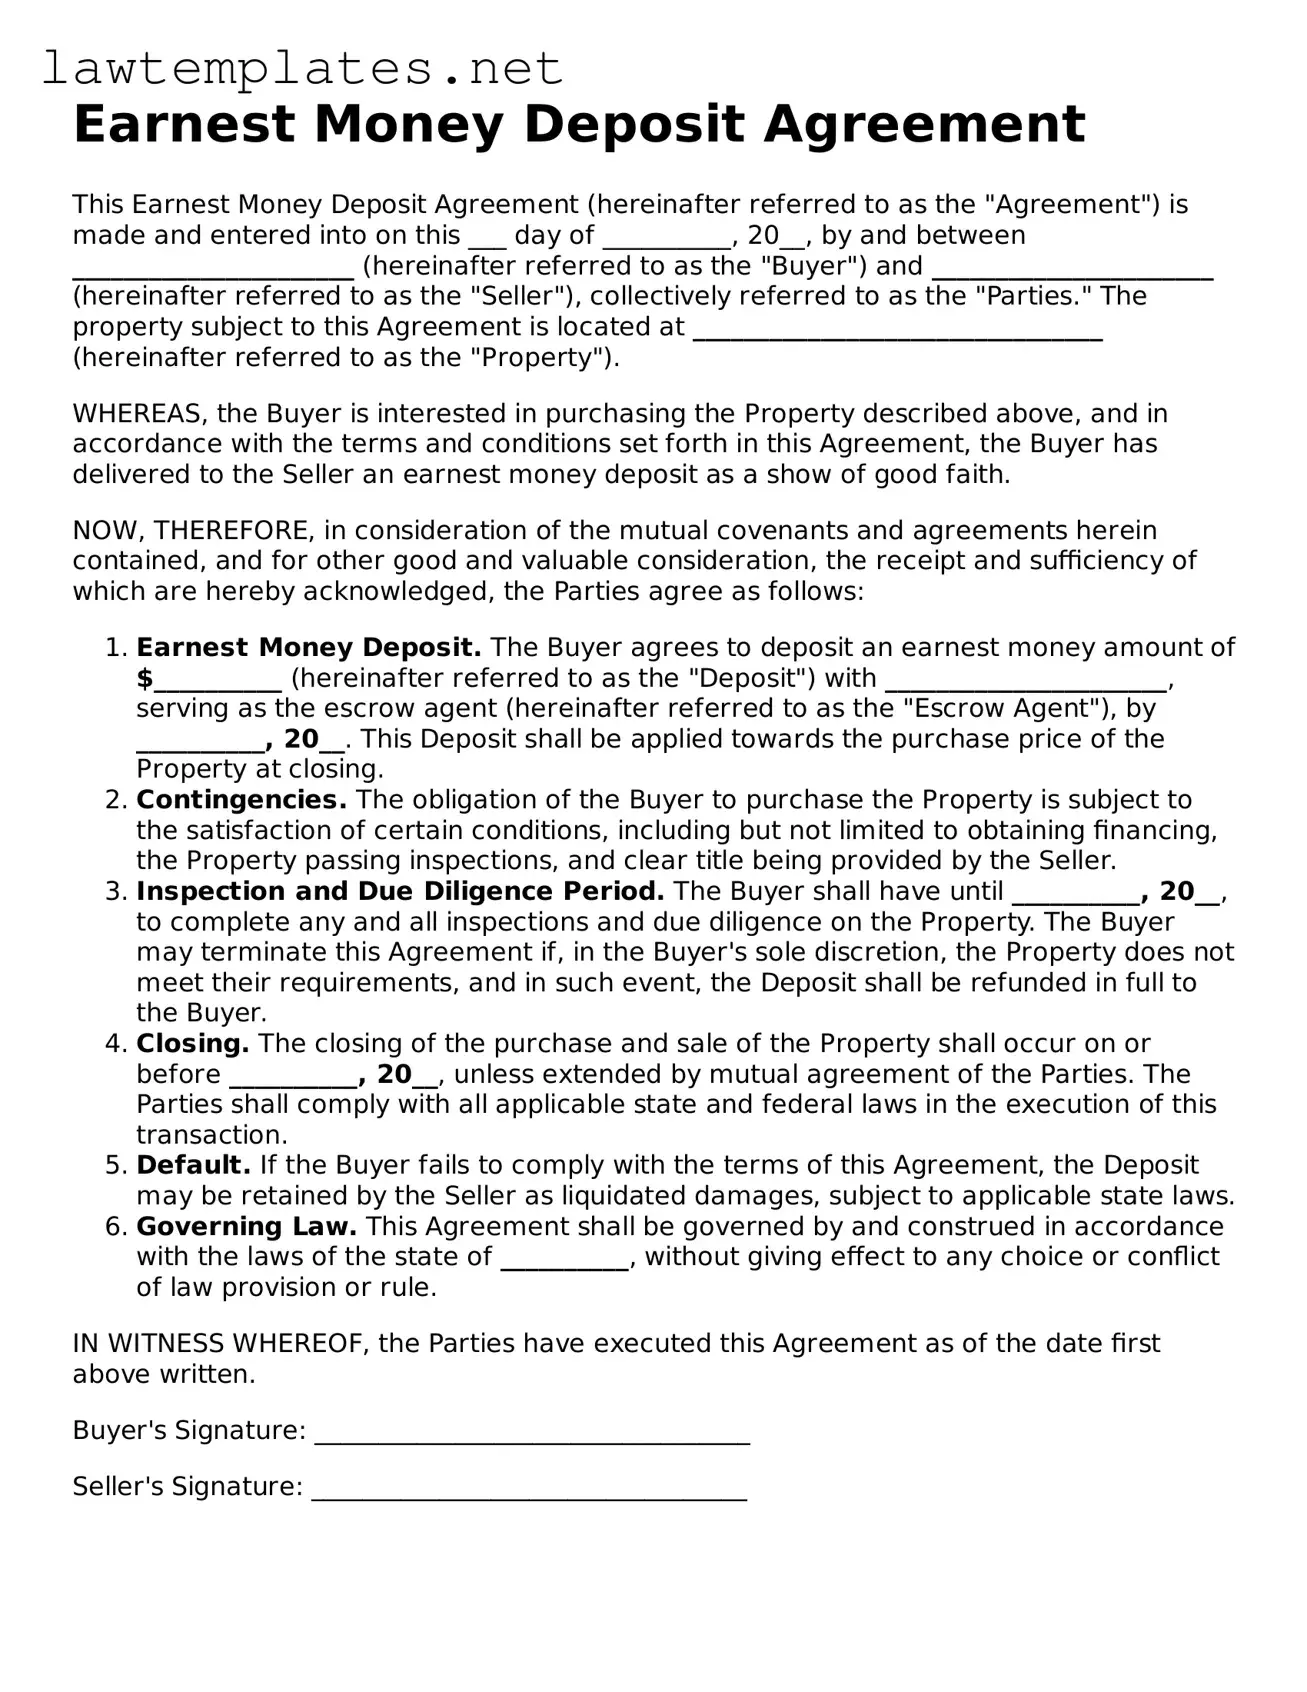
Earnest Money Deposit Agreement Template is the unsung hero of home buying, the little piece of paper that holds your future house’s future together. Think of it as the love letter your future self writes to the future landlord, but with legalese instead of poetry. This blog will walk you through why you need one, how to craft it, and how to keep the paperwork from turning into a full‑blown drama. Ready? Let’s dive in—just don’t forget to bring your sense of humor and a pen that’s not secretly a rubber stamp.
What Exactly Is an Earnest Money Deposit?
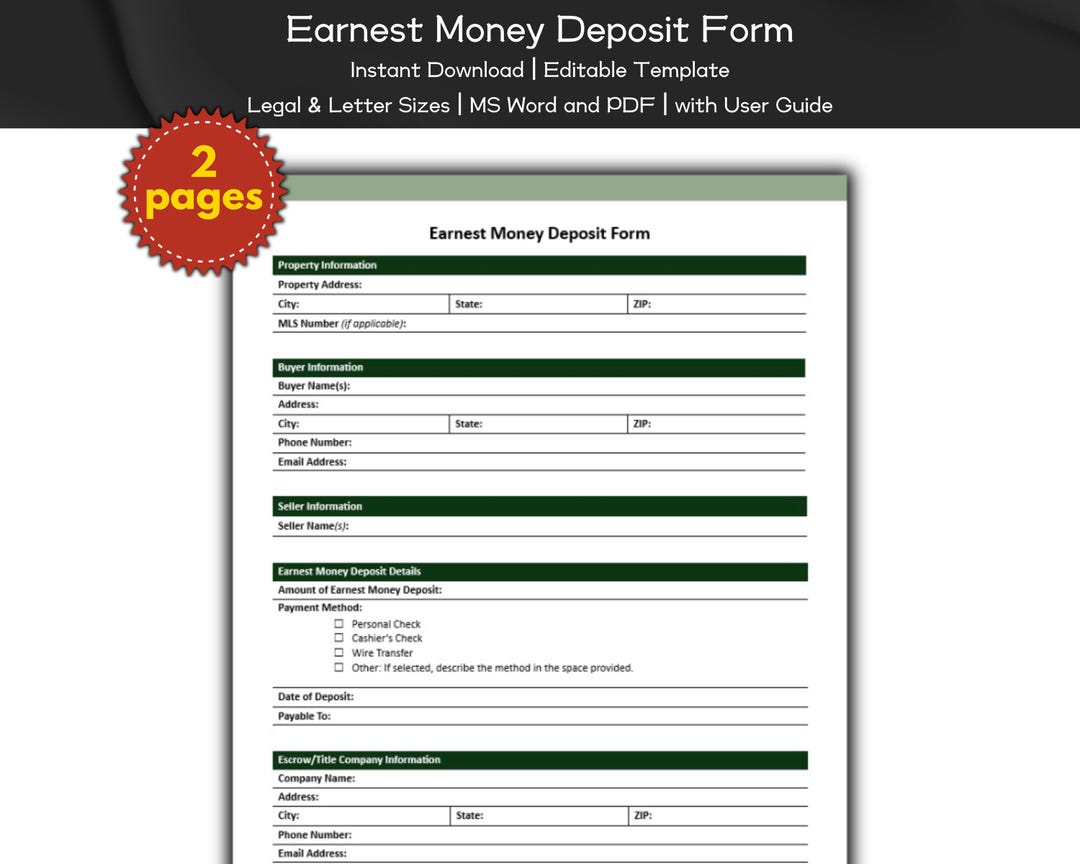
In plain English, an earnest money deposit is the earnest attempt to prove you’re serious about buying a property. It’s a financial handshake between buyer and seller, a little cushion of cash that says, “I’m not here to make a joke; I actually want this house.”
When you sign an agreement, you’re basically saying: “Here’s a dollar, I’ll keep it safe in escrow, and if I back out for reasons that aren’t contract violations, you’ll get it back. If I’m the one who pulls the plug, you get the money.” That’s the basic rulebook. But the actual agreement—our Earnest Money Deposit Agreement Template—gets all the nitty‑gritty details nailed down.
Why You Absolutely Need a Template (and What Makes It Funny)

Without a template, your agreement can be as chaotic as a toddler in a candy store. You might forget to list the deposit amount, the closing date, or the conditions that trigger the refund. The result? A paper trail that looks like a ransom note, and a buyer who can’t prove they were actually serious.
But don’t worry—templates come to the rescue like a superhero in a cape. They give you:
- Consistency: Every clause is in place, so no missing details.
- Clarity: Clear language means fewer arguments about “did the seller mean that?”
- Time‑saving: You get to skip the legal jargon maze.
- Humor (optional): Some templates even let you sprinkle a line or two of wit—just make sure the lawyer approves.
How to Fill Out an Earnest Money Deposit Agreement Template
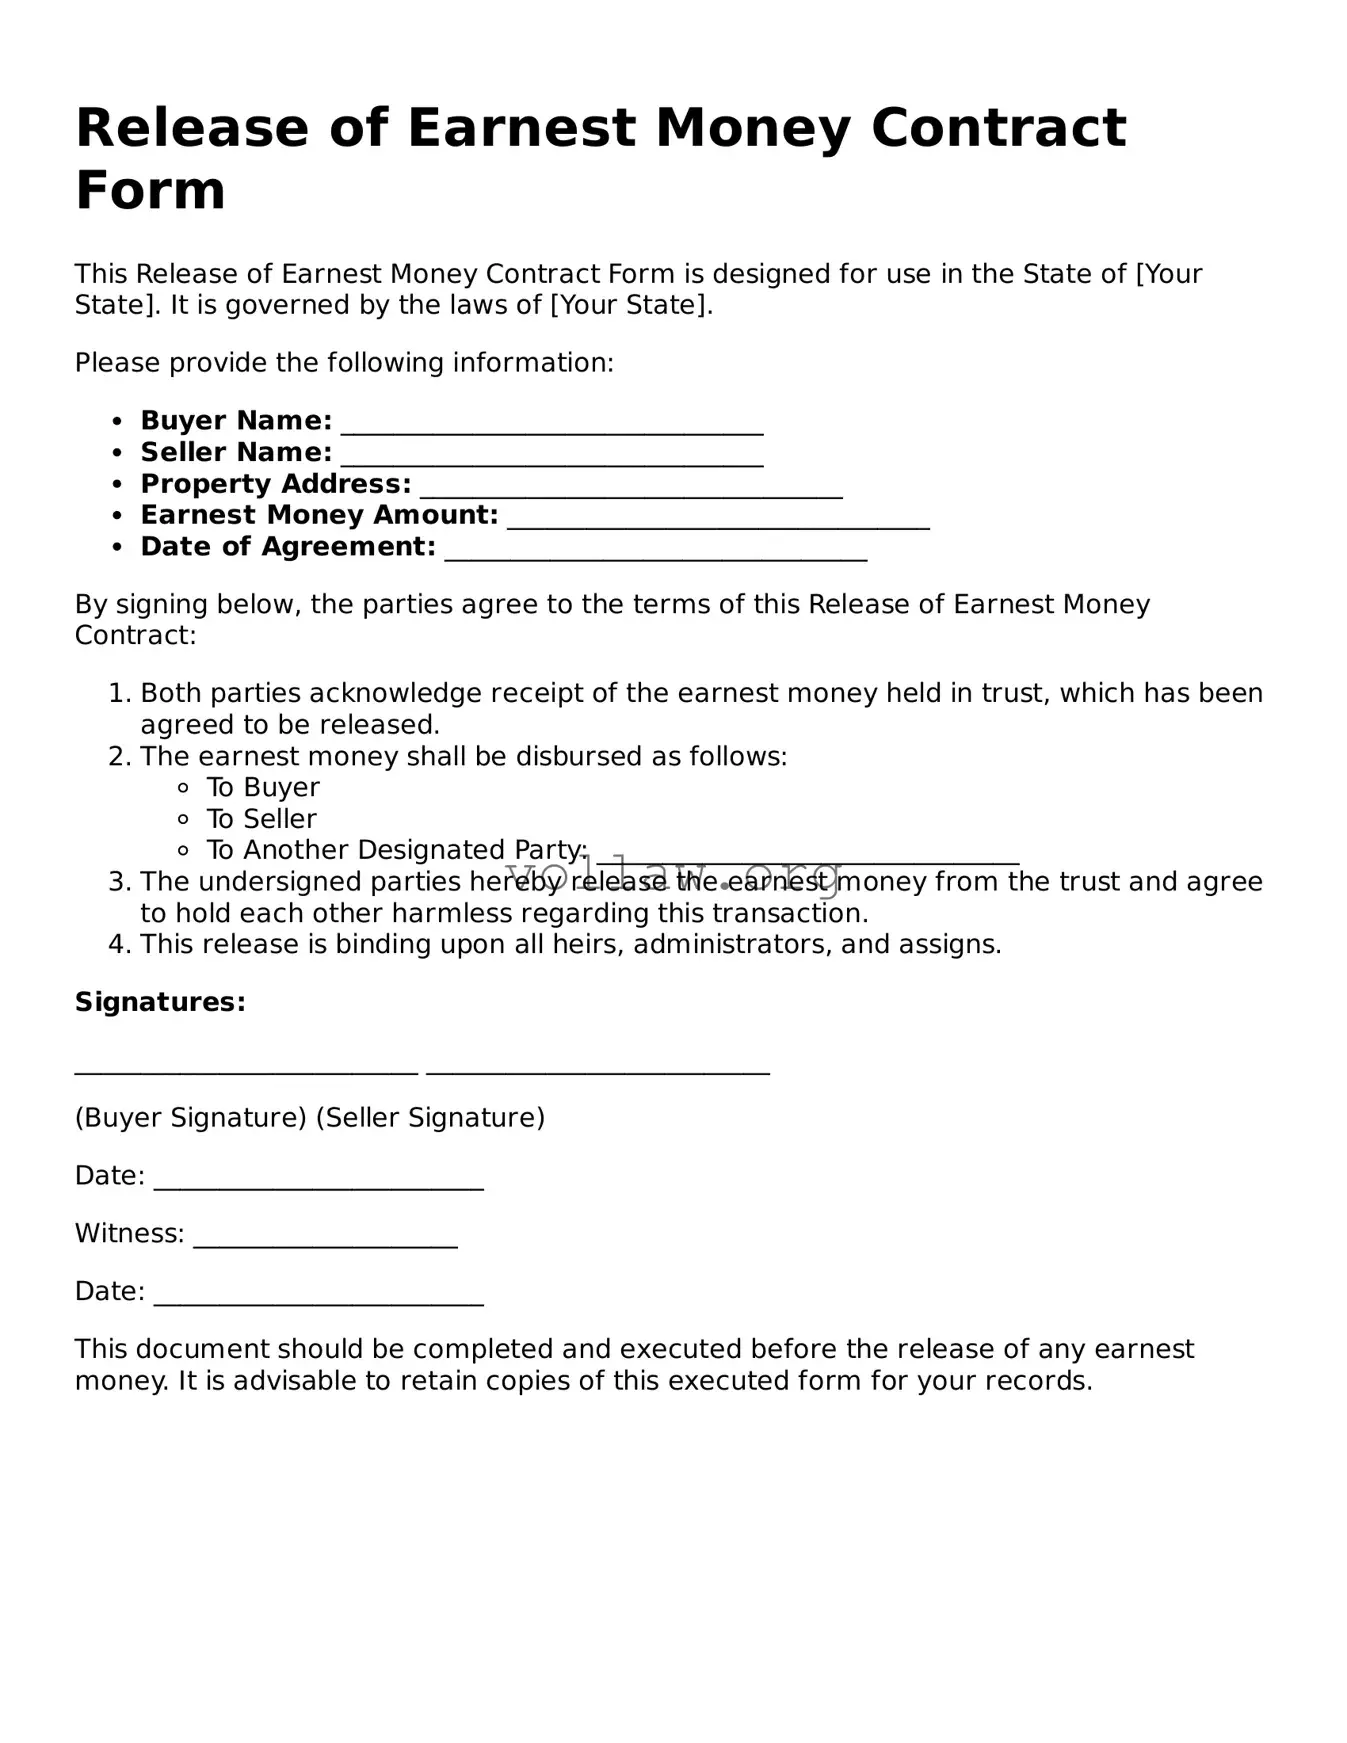
Step 1: Identify the Parties
Every good agreement starts with the who’s and what’s. List the buyer’s full legal name, address, and contact info. Do the same for the seller. Add a line about the real estate agent or attorney if they’re involved. Think of this section like the title card in a movie—everyone’s getting their credits.
Step 2: Detail the Property
State the property’s address, legal description, and any identifying features (e.g., “the house with the garden gnome collection”). The more specific, the better—no one wants a surprise “Oops, you actually bought a cottage in the woods, not a condo in the city.”
Step 3: State the Offer Amount
Here you say, “The purchase price is $X.” This isn’t the earnest deposit itself, but it sets the context. If you’re feeling playful, add a joke in parentheses—just remember the lawyer’s serious side.
Step 4: Specify the Earnest Money Amount
Most contracts require a percentage of the purchase price—usually 1% to 3%. If the property is $300,000, that means a $3,000 to $9,000 deposit. Write it explicitly. Example: “The Buyer shall deposit $3,000 as earnest money.” Add a note: “Deposit to be held in escrow by XYZ Escrow Services.”
Step 5: Define the Escrow and Payment Method
Explain how the money will be handled. Mention the escrow company, the timeline for deposit, and who is responsible for the account’s fees. For instance: “The Buyer will deliver the earnest money by wire transfer to ABC Escrow, with a 48‑hour confirmation period.”
Step 6: List Conditions for Refund or Forfeiture
This is where the drama unfolds. List the conditions under which the buyer gets the money back, and when the seller can keep it. Common clauses include:
- Inspection Period: If the inspection reveals structural damage, the buyer can walk away.
- Financing Contingency: If the buyer fails to secure a mortgage, the deposit is refunded.
- Title Issues: If the title has liens or disputes, the deposit can be returned.
- Seller’s Default: If the seller refuses to close, the buyer gets the money back.
Step 7: Add Timeframes
Every clause needs a deadline. Specify the inspection window (e.g., 7 days), the financing period (e.g., 45 days), and the closing date. Adding a humorous note about a “deadline to decide if you actually want to live there” can lighten the mood but keep the dates solid.
Step 8: Include Signatures and Witnesses
Wrap up with signature lines for buyer, seller, and possibly the real estate agent or attorney. Add a line for a notary if required. It’s the legal equivalent of a selfie at the end of a great party.
Real‑World Example: The Tale of Bob and the Bizarre Basement

Let’s walk through a hypothetical scenario where a template saves the day. Bob, a first‑time buyer, falls in love with a charming bungalow. His agent provides an Earnest Money Deposit Agreement Template that includes a “basement condition clause.” Bob signs, pays the $2,000 deposit, and the contract says the deposit is refundable if the basement is found to be a secret lair of mold.
Three weeks later, the inspection reveals a 15‑ft. water‑logged space that could turn the house into a submarine. Bob calls his agent, who pulls up the contract. Since the basement clause was included, Bob gets his $2,000 back, and no one loses a dollar—or a dream house.
Common Pitfalls and How to Dodge Them
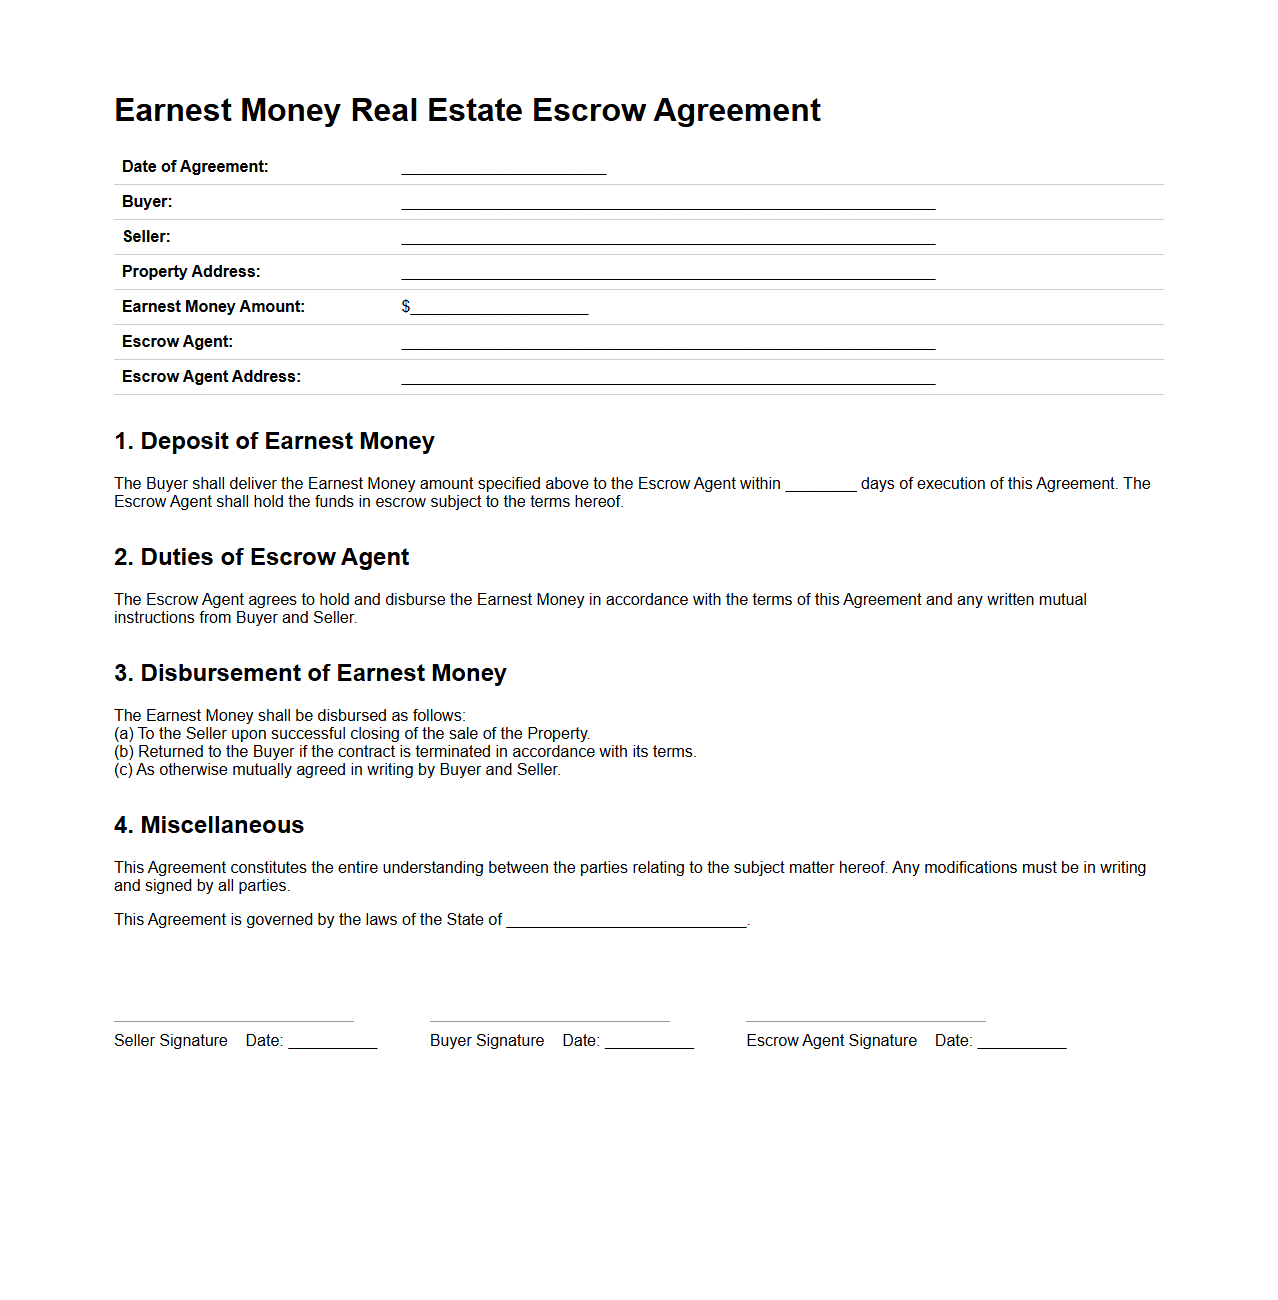
1. Skipping the Escrow Details
Some buyers think they can hand cash to the seller’s hand. That’s a recipe for fraud and a lawsuit. Always specify the escrow company and ensure the deposit is held in a neutral account.
2. Forgetting the Inspection Clause
Without a clear inspection deadline, buyers can hold out forever, and sellers can suffer lost time. Keep the inspection period short but realistic.
3. Using Vague Language
Terms like “reasonable time” or “good faith” are too fuzzy. Use specific dates, percentages, and conditions.
4. Neglecting the Financing Contingency
If you’re relying on a loan, you must include a financing clause. Otherwise, you could be left holding the house with no money.
5. Ignoring the Closing Date
A vague closing date leads to missed deadlines. Pinpoint the exact date or a narrow window.
How to Customize Your Template for Different Situations
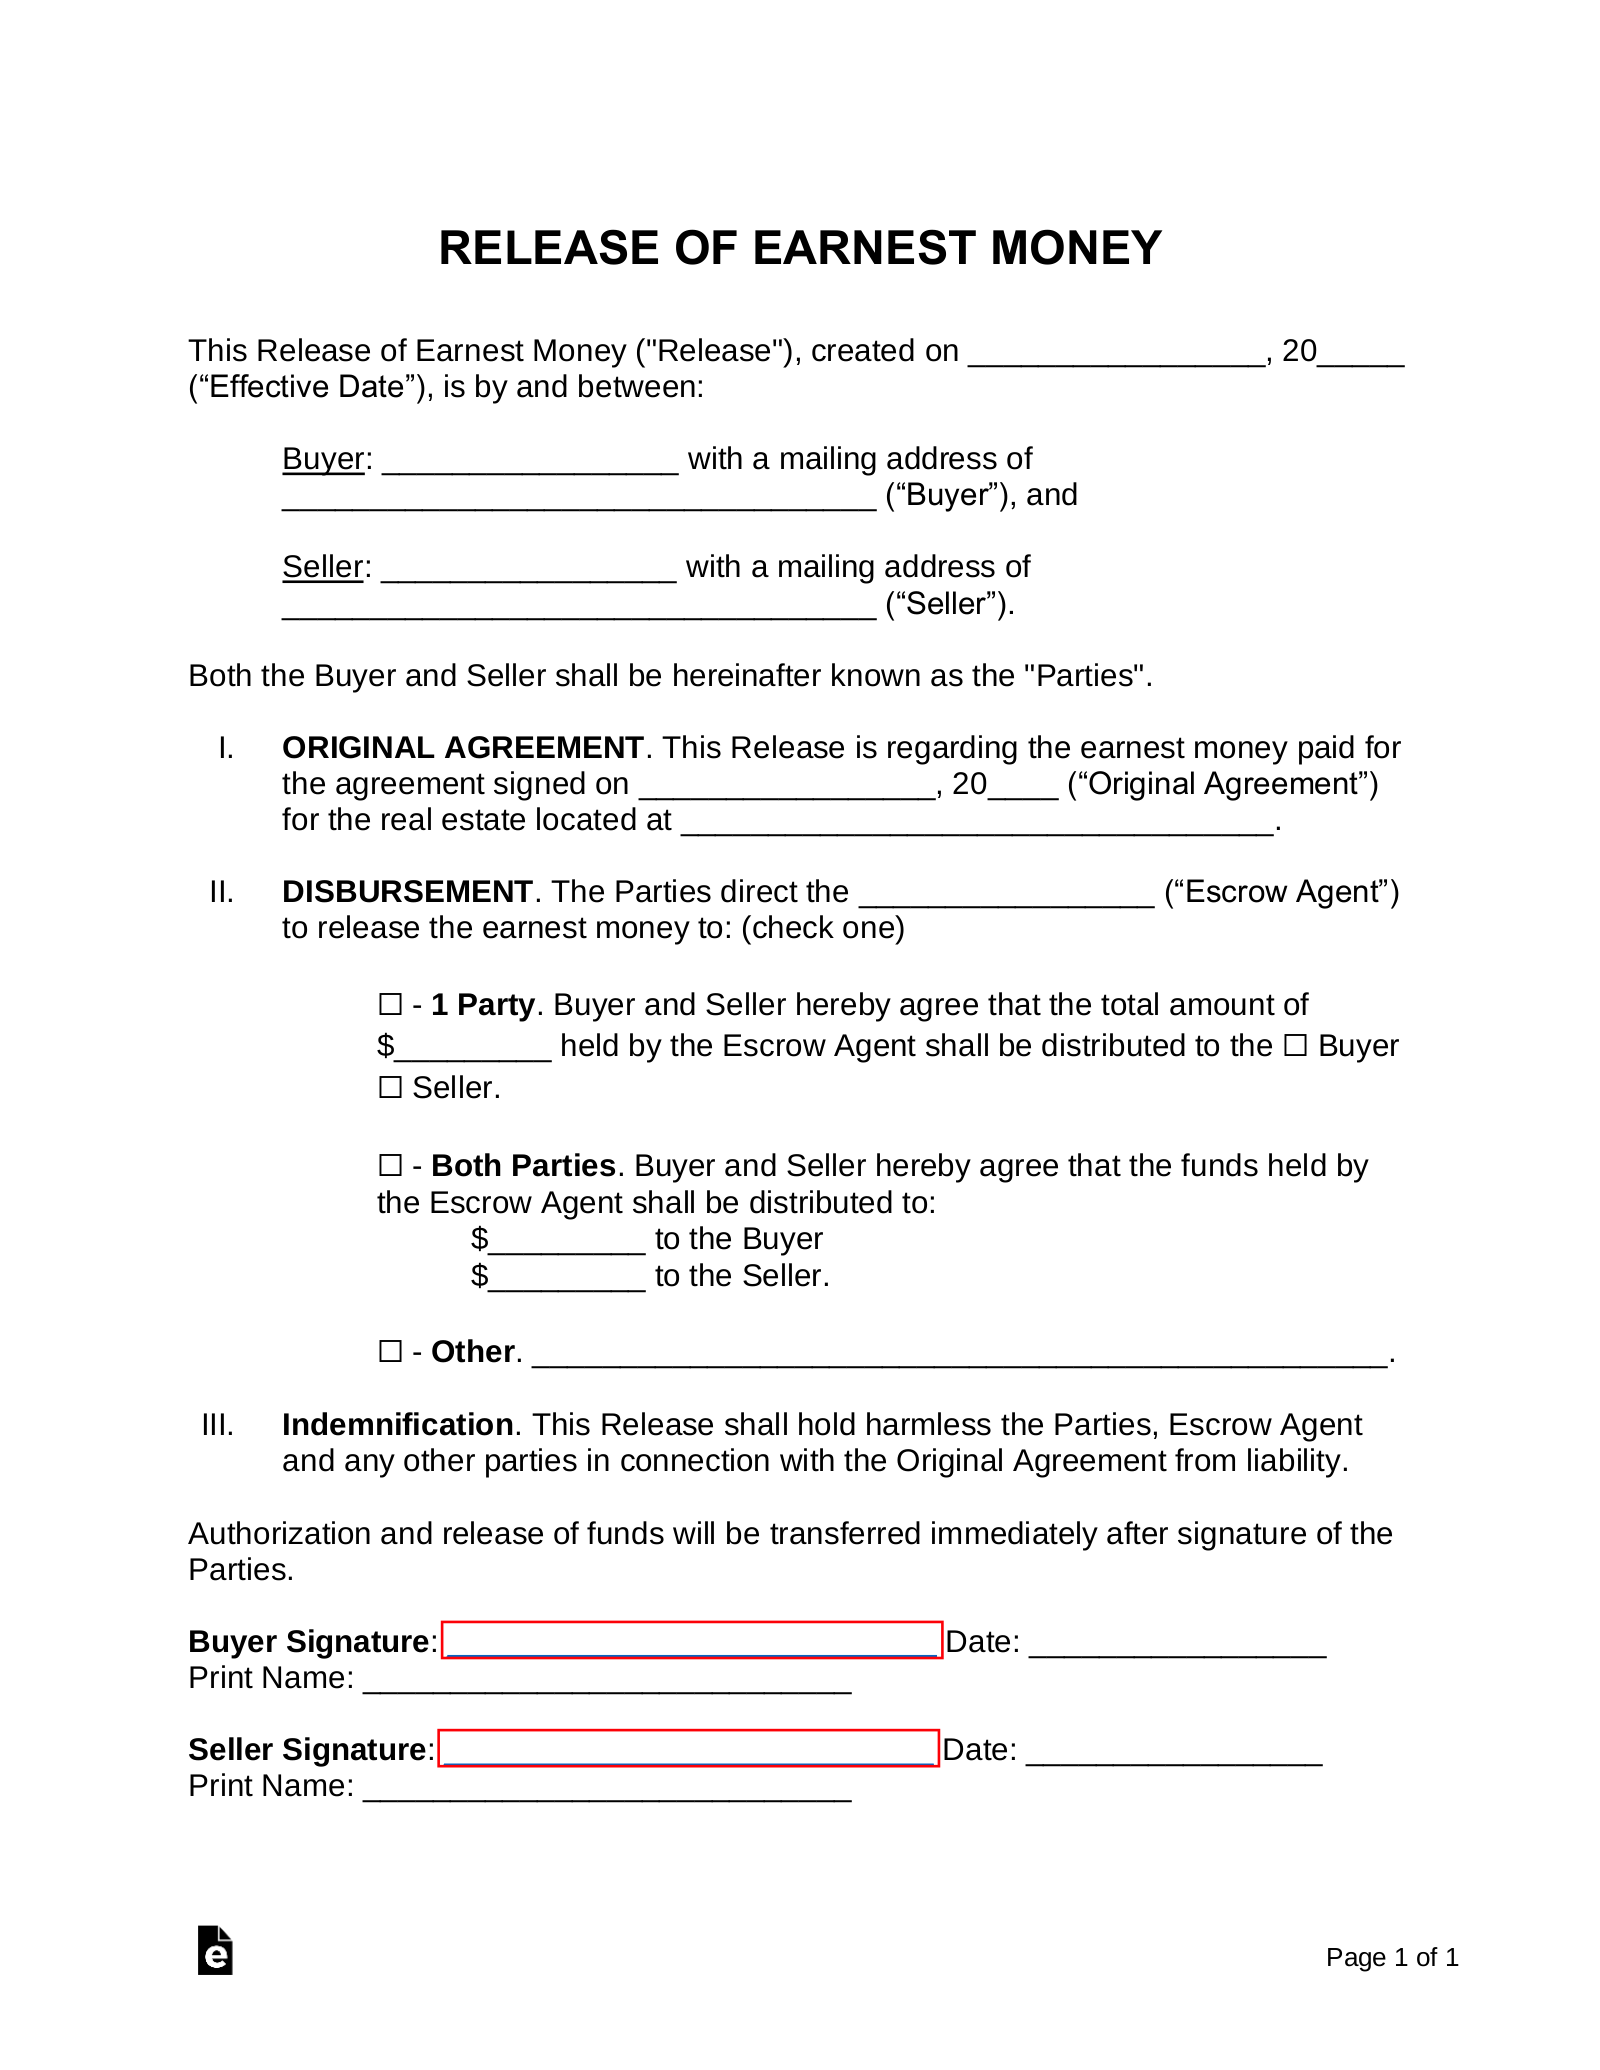
For Luxury Properties
Include additional clauses for appraisal value, special inspections, and high‑value contingencies. Mention the “luxury tax” if applicable.
For Investment Properties
Add a clause that allows the buyer to review financial statements, tenant agreements, and property tax histories.
For Vacation Homes
Include a clause that permits the buyer to test the property during peak seasons and ensure all amenities function.
For Rental Agreements (Commercial)
Swap “purchase price” for “lease amount” and adjust the earnest deposit to reflect a lease guarantee rather than a down payment.
Legal Considerations: The Non‑Comedy Section
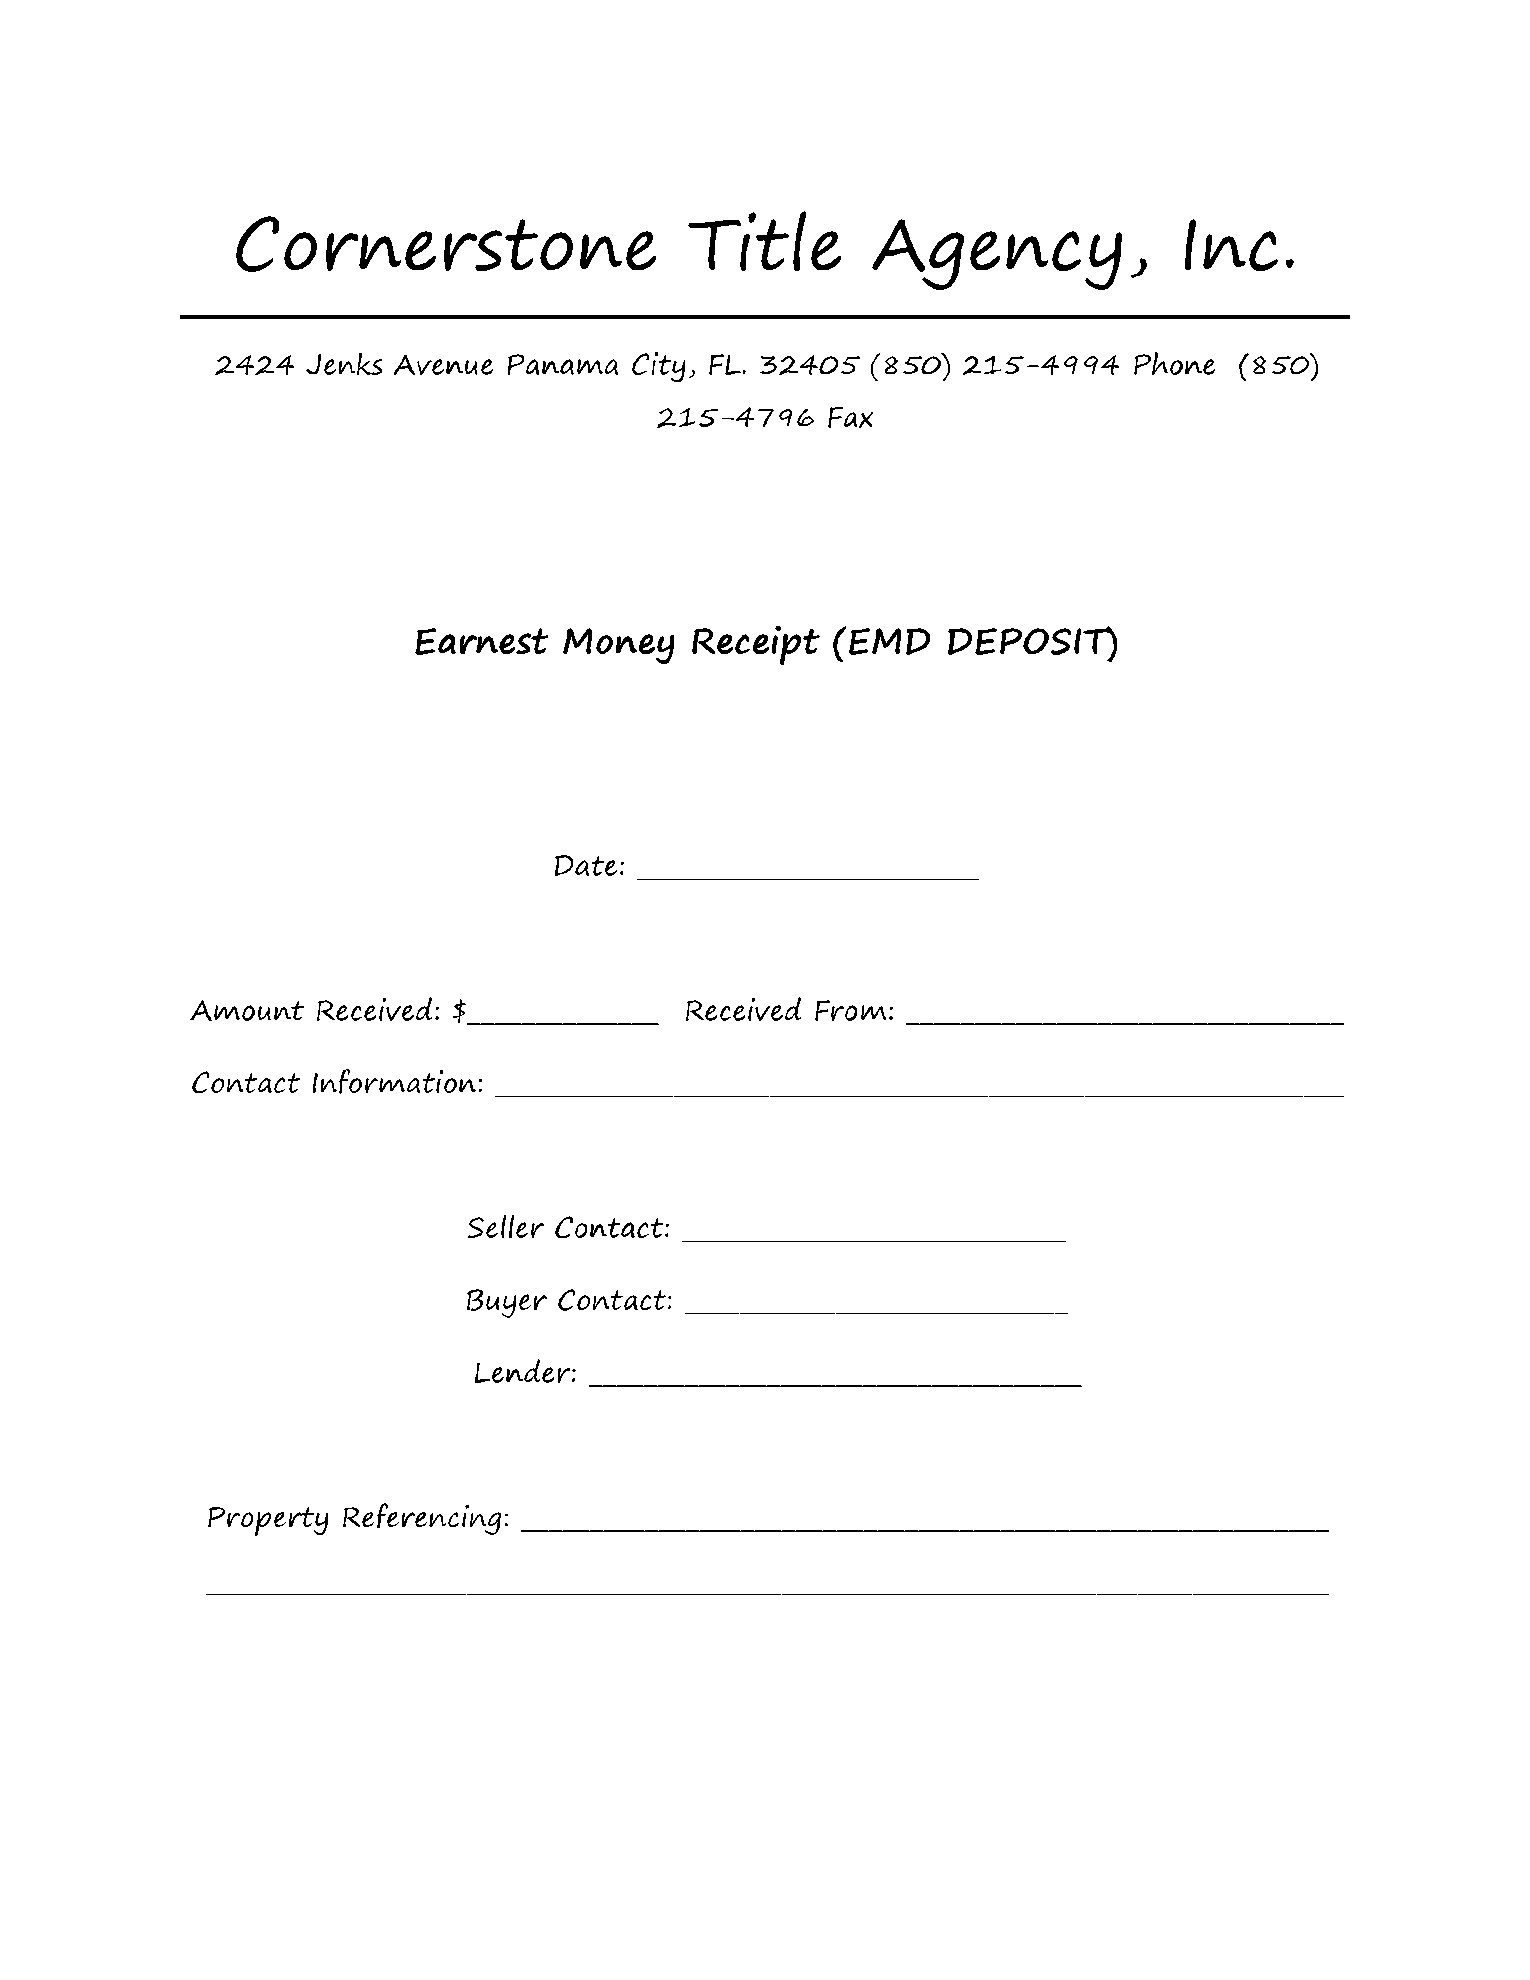
While humor keeps the tone light, the contract itself must remain legally binding. Here are some must‑know points:
- Jurisdiction: Specify the state and county’s laws that govern the agreement.
- Dispute Resolution: Include a clause that states disputes will be handled through mediation or arbitration.
- Notary: Some states require notarization of the earnest money agreement.
- Compliance: Ensure the template meets local real estate regulations and licensing requirements.
Tips for Using the Template Effectively
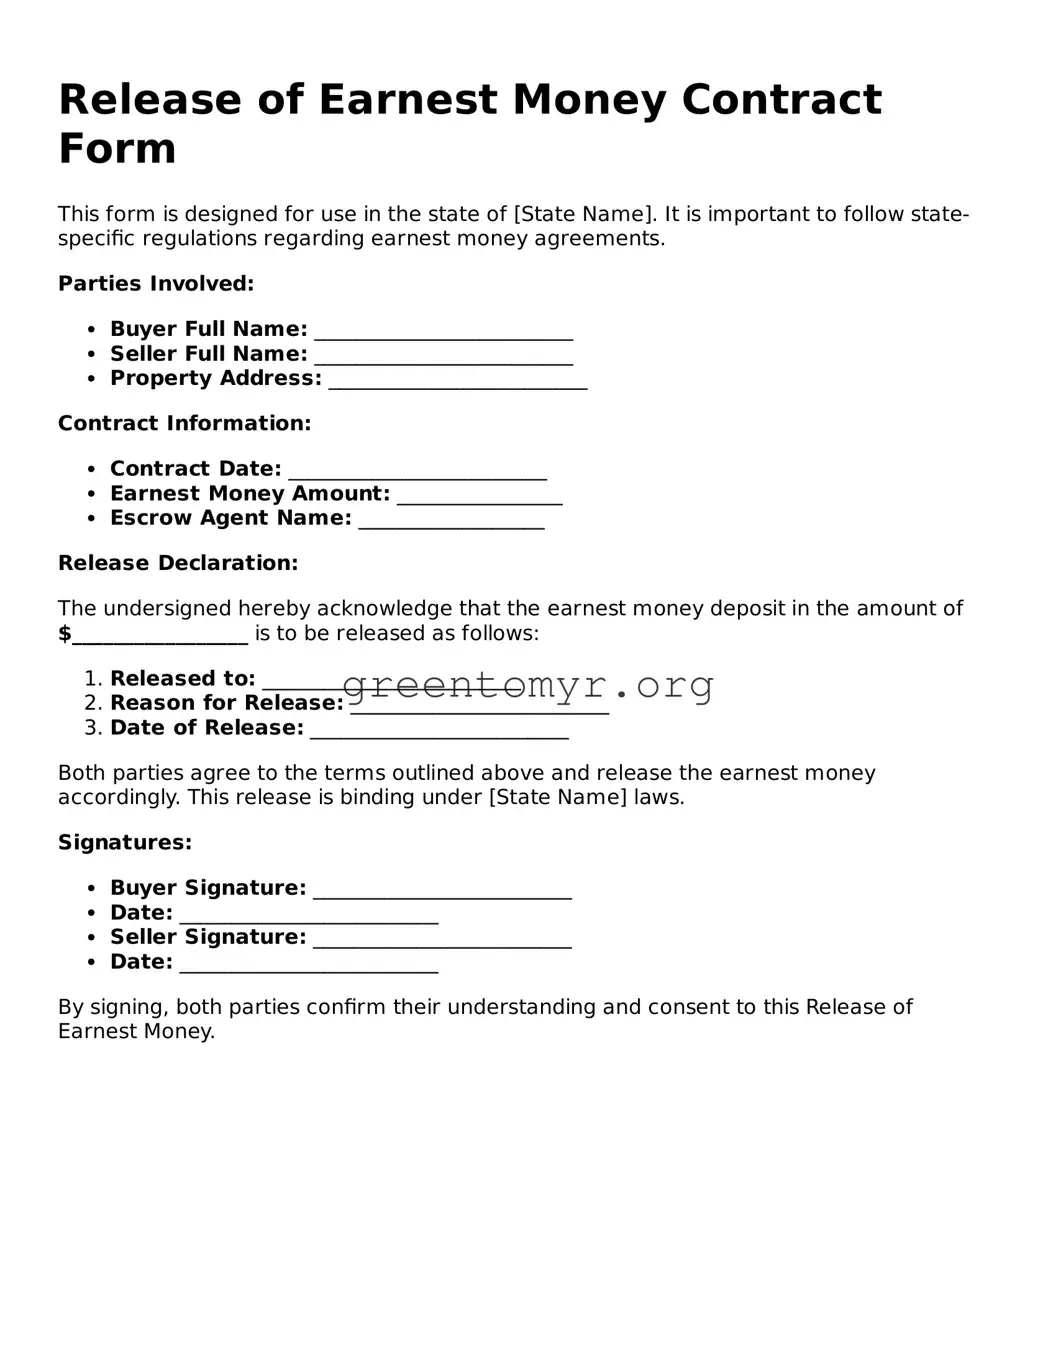
1. Read It Thoroughly Before Signing
Don’t skim. Every clause matters, especially the ones that protect you from being stuck with a bad deal.
2. Keep Copies
Store a signed PDF in the cloud and a paper copy in your folder. That way, you won’t lose track of the document during the closing frenzy.
3. Double‑Check the Deposit Amount
It’s easy to misread a number. Confirm the amount matches your expectations.
4. Verify Escrow Company Credentials
Make sure the escrow provider is licensed and reputable. A bad escrow can be a nightmare.
5. Seek Legal Review
Even if you trust the template, have a real estate attorney glance over it to avoid hidden pitfalls.
Frequently Asked Questions (FAQs)
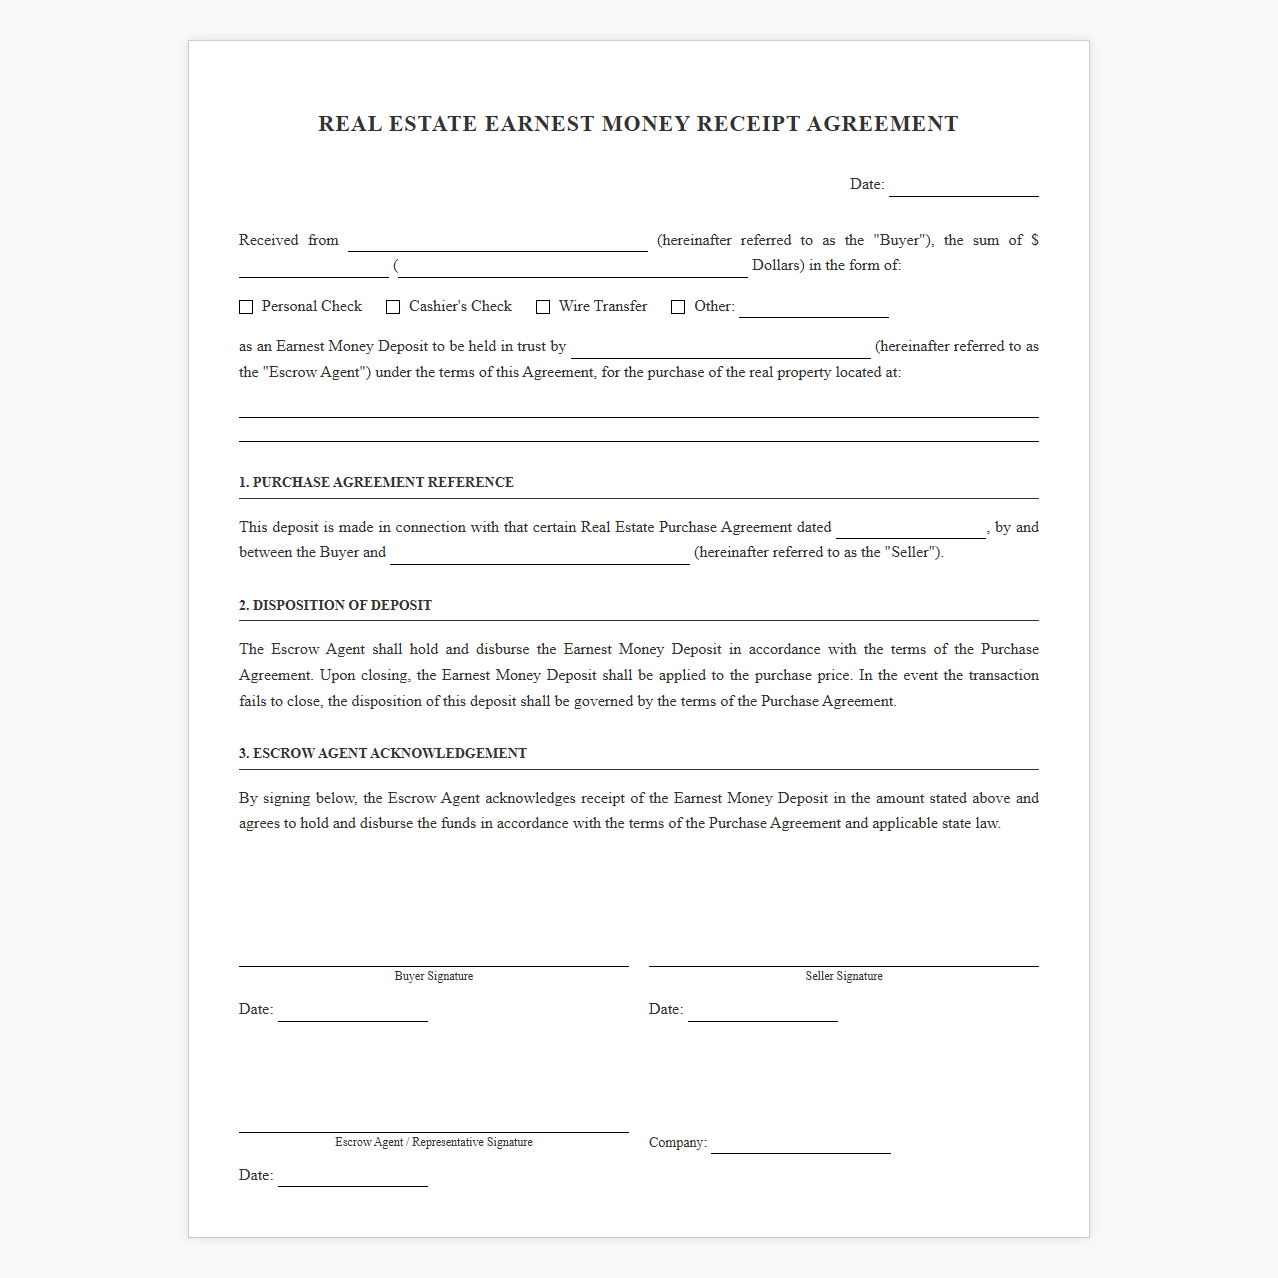
What happens if the seller refuses to close?
If the seller breaches the contract, the buyer typically gets a full refund of the earnest money, and may also pursue damages.
Can I use the earnest money for a different property?
No—unless the contract specifies a “contingent” transfer, the funds are tied to that specific transaction.
Do I need a lawyer to fill out the template?
No, but a lawyer’s review can prevent costly mistakes.
Is a higher earnest deposit a sign of seriousness?
Sometimes. A larger deposit can signal strong intent, but it also raises the stakes. Balance caution with commitment.
What if the inspection finds nothing but a funky smell?
Make sure the template has a clause covering odor or “mysterious scents” that could indicate deeper problems.
The Bottom Line: Why Your Home Buying Journey Deserves a Template
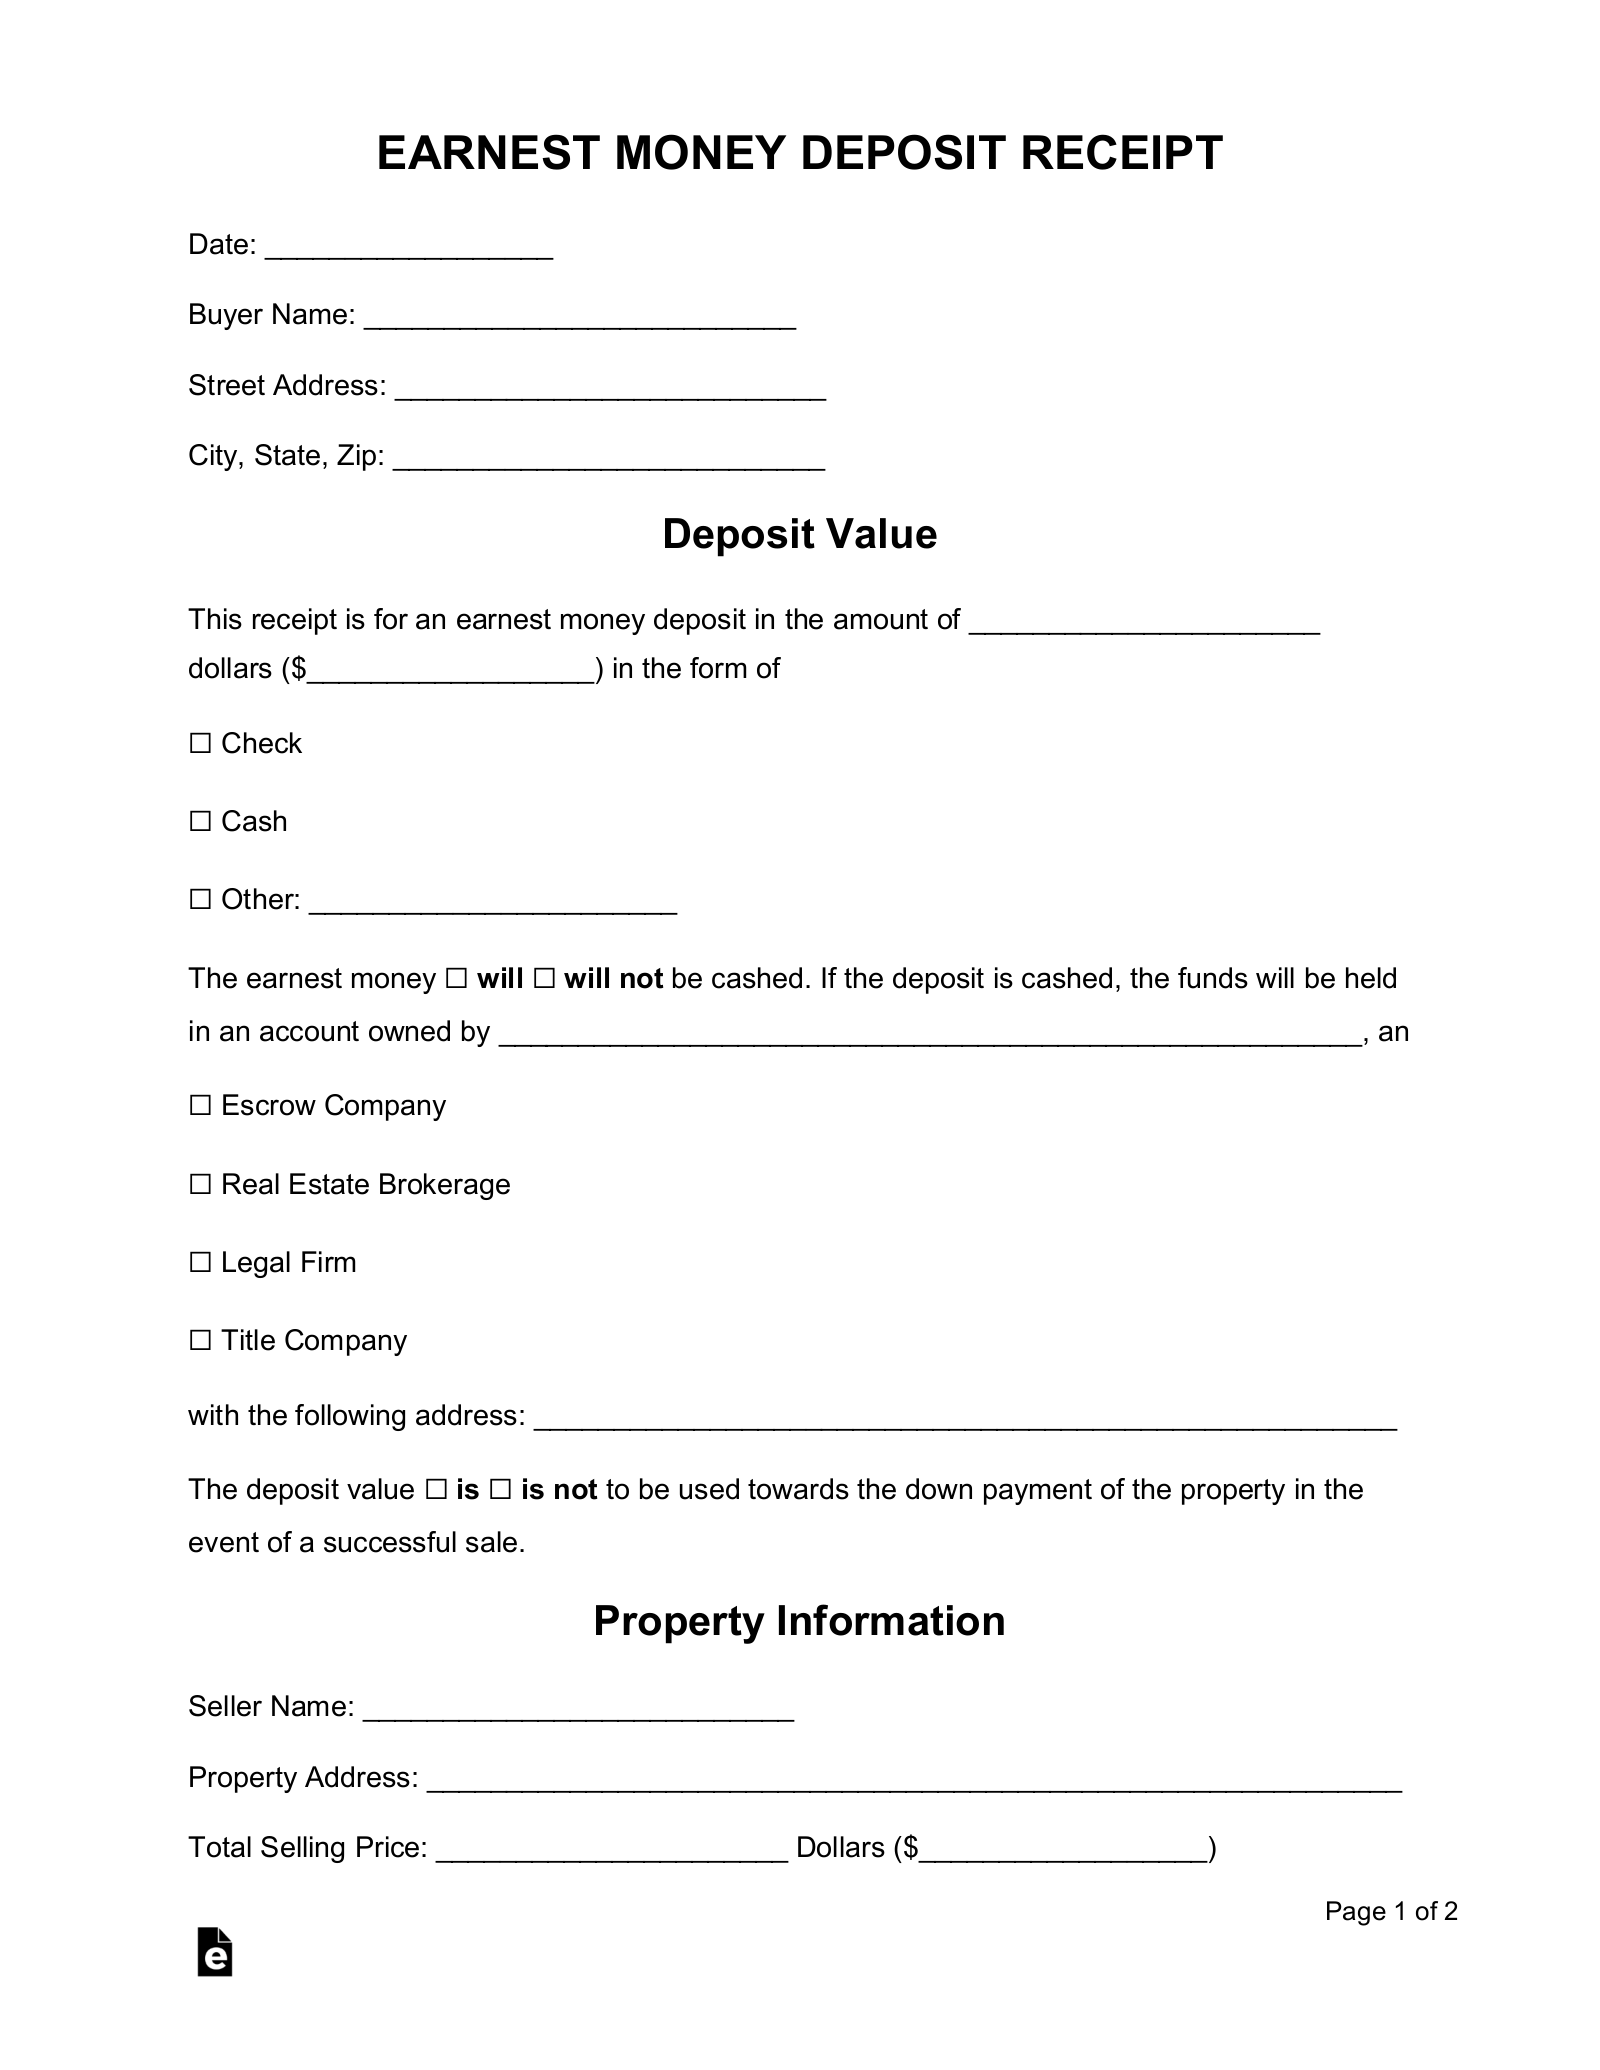
In the whirlwind world of real estate, an Earnest Money Deposit Agreement Template serves as your trusty roadmap. It clarifies expectations, protects your money, and keeps the negotiation process from turning into a courtroom drama. With the right template, you can confidently step into the role of a buyer, knowing every dollar is safeguarded and every clause is crystal clear.
Remember: a well‑crafted agreement is your ticket to smooth closing, fewer surprises, and a whole lot less drama. So next time you find yourself staring at a stack of legal jargon, take a deep breath, grab a coffee, and let your template guide you through the maze. After all, home buying is a serious business—just don’t forget to bring a smile along the way.